Resources
Guides, research, and perspectives on R&D intelligence, IP strategy, and the future of AI enabled innovation.
Executive Summary
In 2024, US patent infringement jury verdicts totaled $4.19 billion across 72 cases. Twelve individual verdicts exceeded $100million. The largest single award—$857 million in General Access Solutions v.Cellco Partnership (Verizon)—exceeded the annual R&D budget of many mid-market technology companies. In the first half of 2025 alone, total damages reached an additional $1.91 billion.
The consequences of incomplete patent intelligence are not abstract. In what has become one of the most instructive IP disputes in recent history, Masimo’s pulse oximetry patents triggered a US import ban on certain Apple Watch models, forcing Apple to disable its blood oxygen feature across an entire product line, halt domestic sales of affected models, invest in a hardware redesign, and ultimately face a $634 million jury verdict in November 2025. Apple—a company with one of the most sophisticated intellectual property organizations on earth—spent years in litigation over technology it might have designed around during development.
For organizations with fewer resources than Apple, the risk calculus is starker. A mid-size materials company, a university spinout, or a defense contractor developing next-generation battery technology cannot absorb a nine-figure verdict or a multi-year injunction. For these organizations, the patent landscape analysis conducted during the development phase is the primary risk mitigation mechanism. The quality of that analysis is not a matter of convenience. It is a matter of survival.
And yet, a growing number of R&D and IP teams are conducting that analysis using general-purpose AI tools—ChatGPT, Claude, Microsoft Co-Pilot—that were never designed for patent intelligence and are structurally incapable of delivering it.
This report presents the findings of a controlled comparison study in which identical patent landscape queries were submitted to four AI-powered tools: Cypris (a purpose-built R&D intelligence platform),ChatGPT (OpenAI), Claude (Anthropic), and Microsoft Co-Pilot. Two technology domains were tested: solid-state lithium-sulfur battery electrolytes using garnet-type LLZO ceramic materials (freedom-to-operate analysis), and bio-based polyamide synthesis from castor oil derivatives (competitive intelligence).
The results reveal a significant and structurally persistent gap. In Test 1, Cypris identified over 40 active US patents and published applications with granular FTO risk assessments. Claude identified 12. ChatGPT identified 7, several with fabricated attribution. Co-Pilot identified 4. Among the patents surfaced exclusively by Cypris were filings rated as “Very High” FTO risk that directly claim the technology architecture described in the query. In Test 2, Cypris cited over 100 individual patent filings with full attribution to substantiate its competitive landscape rankings. No general-purpose model cited a single patent number.
The most active sectors for patent enforcement—semiconductors, AI, biopharma, and advanced materials—are the same sectors where R&D teams are most likely to adopt AI tools for intelligence workflows. The findings of this report have direct implications for any organization using general-purpose AI to inform patent strategy, competitive intelligence, or R&D investment decisions.

1. Methodology
A controlled comparative evaluation was conducted on March 27, 2026. An identical patent landscape query was submitted verbatim to each platform under standardized testing conditions. No follow-up prompts, clarifications, or iterative refinements were permitted, ensuring that each platform was evaluated based solely on its initial response.
The outputs were preserved in their original form and evaluated against predefined criteria using publicly verifiable patent records.
1.1 Query
Identify all active US patents and published applications filed in the last 5 years related to solid-state lithium-sulfur battery electrolytes using garnet-type ceramic materials. For each, provide the assignee, filing date, key claims, and current legal status. Highlight any patents that could pose freedom-to-operate risks for a company developing a Li₇La₃Zr₂O₁₂(LLZO)-based composite electrolyte with a polymer interlayer.
1.2 Tools Evaluated

1.3 Evaluation Criteria
Each response was evaluated using a consistent six-part scoring framework: patent coverage, assignee accuracy, filing metadata completeness, depth of claim analysis, quality of FTO risk stratification, and the presence of actionable strategic guidance.
Patent numbers, assignees, filing information, and legal status were independently checked against publicly available USPTO and WIPO records. The evaluation focused on the completeness, accuracy, and practical utility of each platform’s output rather than writing quality or presentation.
2. Findings
2.1 Coverage Gap
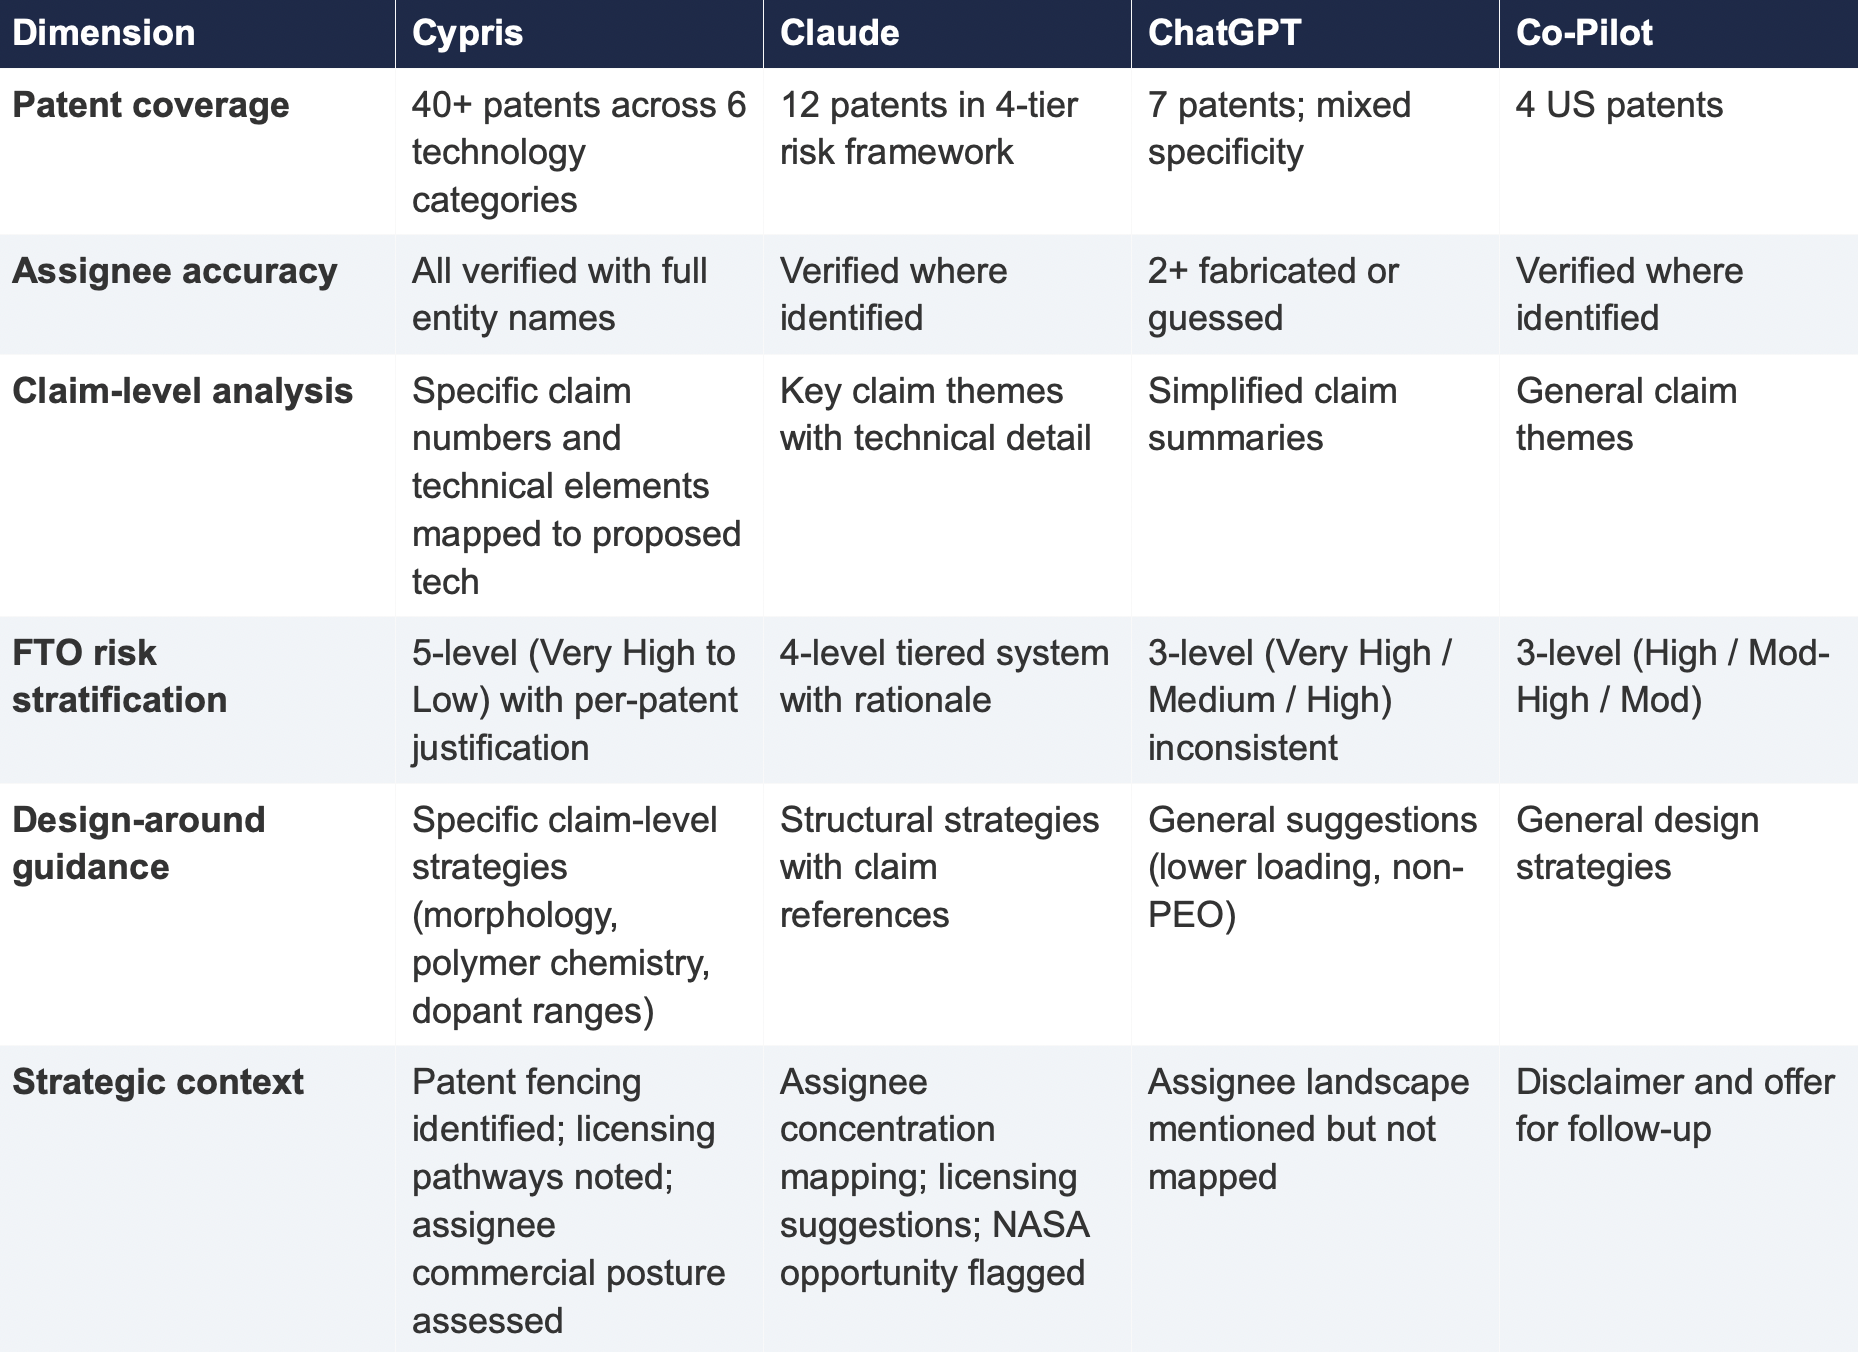
The most significant finding is the scale of the coverage differential. Cypris identified over 40 active US patents and published applications spanning LLZO-polymer composite electrolytes, garnet interface modification, polymer interlayer architectures, lithium-sulfur specific filings, and adjacent ceramic composite patents. The results were organized by technology category with per-patent FTO risk ratings.
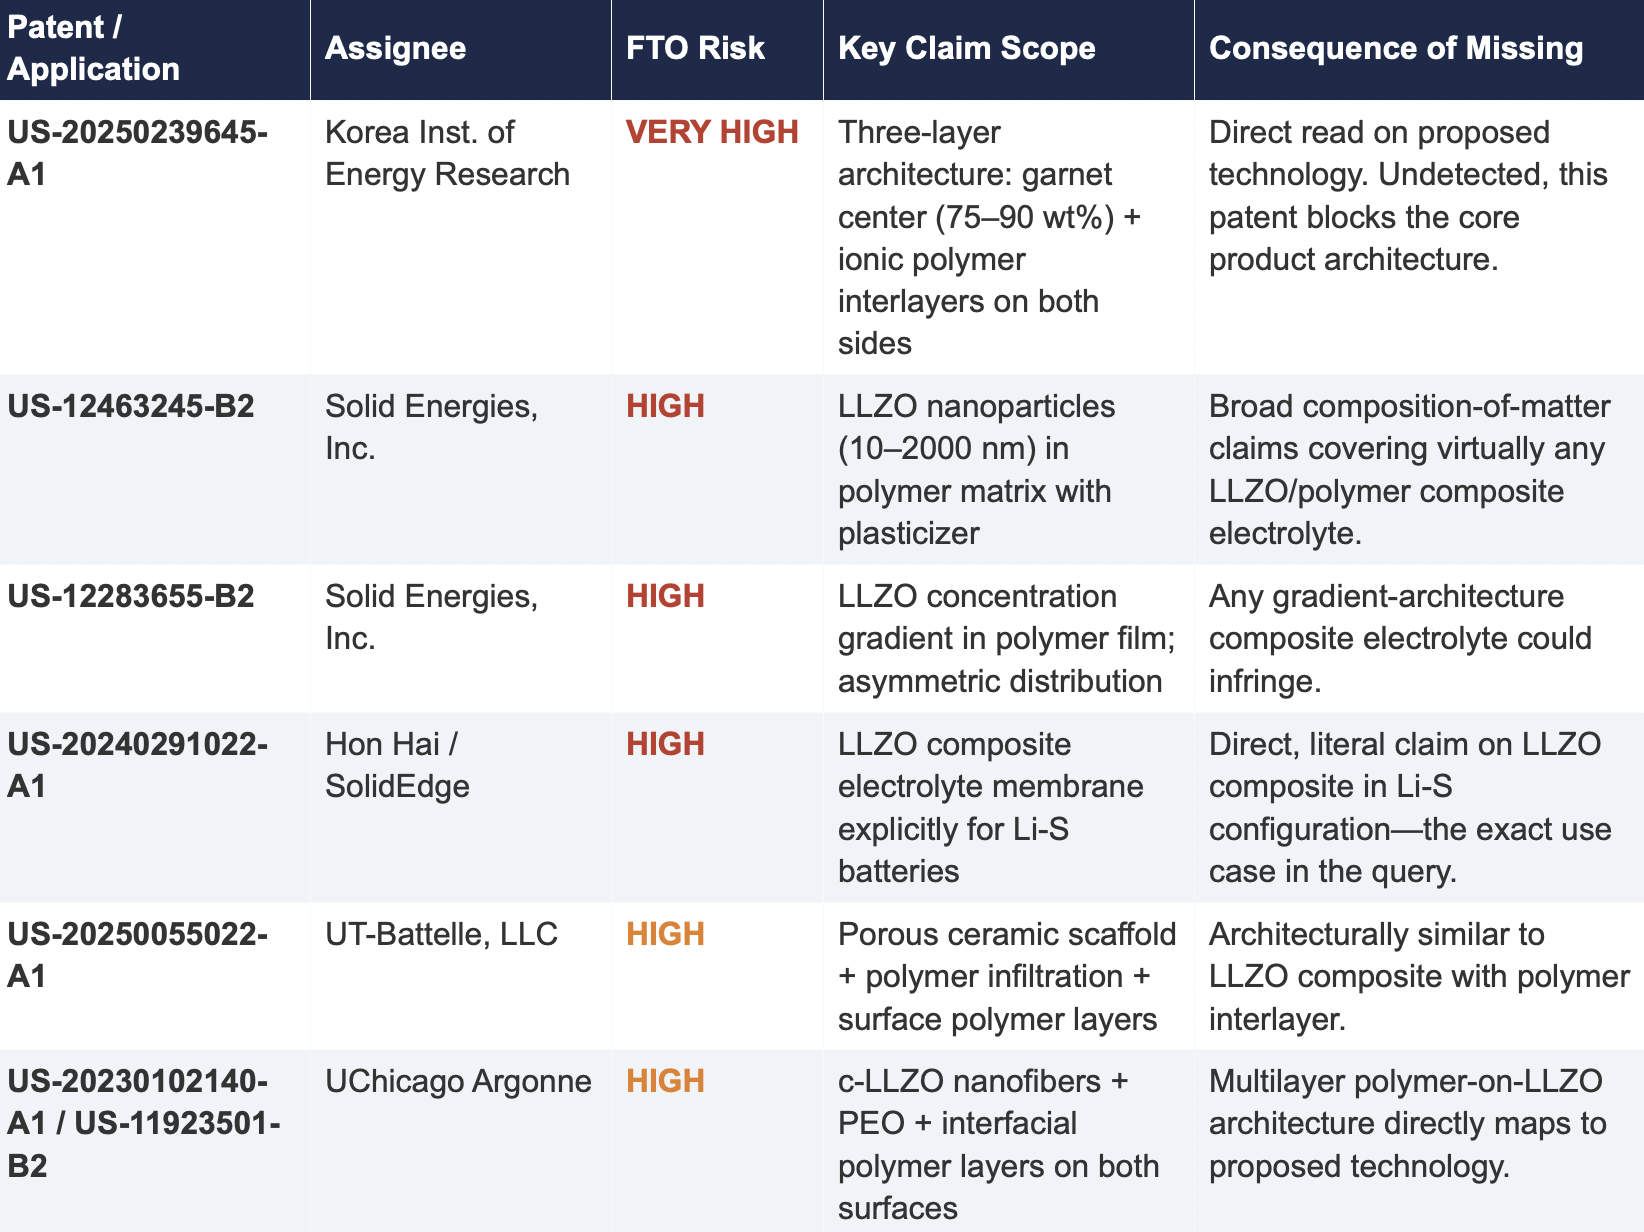
Claude identified 12 patents organized in a four-tier risk framework. Its analysis was structurally sound and correctly flagged the two highest-risk filings (Solid Energies US 11,967,678 and the LLZO nanofiber multilayer US 11,923,501). It also identified the University ofMaryland/ Wachsman portfolio as a concentration risk and noted the NASA SABERS portfolio as a licensing opportunity. However, it missed the majority of the landscape, including the entire Corning portfolio, GM's interlayer patents, theKorea Institute of Energy Research three-layer architecture, and the HonHai/SolidEdge lithium-sulfur specific filing.
ChatGPT identified 7 patents, but the quality of attribution was inconsistent. It listed assignees as "Likely DOE /national lab ecosystem" and "Likely startup / defense contractor cluster" for two filings—language that indicates the model was inferring rather than retrieving assignee data. In a freedom-to-operate context, an unverified assignee attribution is functionally equivalent to no attribution, as it cannot support a licensing inquiry or risk assessment.
Co-Pilot identified 4 US patents. Its output was the most limited in scope, missing the Solid Energies portfolio entirely, theUMD/ Wachsman portfolio, Gelion/ Johnson Matthey, NASA SABERS, and all Li-S specific LLZO filings.
2.2 Critical Patents Missed by Public Models
The following table presents patents identified exclusively by Cypris that were rated as High or Very High FTO risk for the proposed technology architecture. None were surfaced by any general-purpose model.
2.3 Patent Fencing: The Solid Energies Portfolio
Cypris identified a coordinated patent fencing strategy by Solid Energies, Inc. that no general-purpose model detected at scale. Solid Energies holds at least four granted US patents and one published application covering LLZO-polymer composite electrolytes across compositions(US-12463245-B2), gradient architectures (US-12283655-B2), electrode integration (US-12463249-B2), and manufacturing processes (US-20230035720-A1). Claude identified one Solid Energies patent (US 11,967,678) and correctly rated it as the highest-priority FTO concern but did not surface the broader portfolio. ChatGPT and Co-Pilot identified zero Solid Energies filings.
The practical significance is that a company relying on any individual patent hit would underestimate the scope of Solid Energies' IP position. The fencing strategy—covering the composition, the architecture, the electrode integration, and the manufacturing method—means that identifying a single design-around for one patent does not resolve the FTO exposure from the portfolio as a whole. This is the kind of strategic insight that requires seeing the full picture, which no general-purpose model delivered
2.4 Assignee Attribution Quality
ChatGPT's response included at least two instances of fabricated or unverifiable assignee attributions. For US 11,367,895 B1, the listed assignee was "Likely startup / defense contractor cluster." For US 2021/0202983 A1, the assignee was described as "Likely DOE / national lab ecosystem." In both cases, the model appears to have inferred the assignee from contextual patterns in its training data rather than retrieving the information from patent records.
In any operational IP workflow, assignee identity is foundational. It determines licensing strategy, litigation risk, and competitive positioning. A fabricated assignee is more dangerous than a missing one because it creates an illusion of completeness that discourages further investigation. An R&D team receiving this output might reasonably conclude that the landscape analysis is finished when it is not.
3. Structural Limitations of General-Purpose Models for Patent Intelligence
3.1 Training Data Is Not Patent Data
Large language models are trained on web-scraped text. Their knowledge of the patent record is derived from whatever fragments appeared in their training corpus: blog posts mentioning filings, news articles about litigation, snippets of Google Patents pages that were crawlable at the time of data collection. They do not have systematic, structured access to the USPTO database. They cannot query patent classification codes, parse claim language against a specific technology architecture, or verify whether a patent has been assigned, abandoned, or subjected to terminal disclaimer since their training data was collected.
This is not a limitation that improves with scale. A larger training corpus does not produce systematic patent coverage; it produces a larger but still arbitrary sampling of the patent record. The result is that general-purpose models will consistently surface well-known patents from heavily discussed assignees (QuantumScape, for example, appeared in most responses) while missing commercially significant filings from less publicly visible entities (Solid Energies, Korea Institute of EnergyResearch, Shenzhen Solid Advanced Materials).
3.2 The Web Is Closing to Model Scrapers
The data access problem is structural and worsening. As of mid-2025, Cloudflare reported that among the top 10,000 web domains, the majority now fully disallow AI crawlers such as GPTBot andClaudeBot via robots.txt. The trend has accelerated from partial restrictions to outright blocks, and the crawl-to-referral ratios reveal the underlying tension: OpenAI's crawlers access approximately1,700 pages for every referral they return to publishers; Anthropic's ratio exceeds 73,000 to 1.
Patent databases, scientific publishers, and IP analytics platforms are among the most restrictive content categories. A Duke University study in 2025 found that several categories of AI-related crawlers never request robots.txt files at all. The practical consequence is that the knowledge gap between what a general-purpose model "knows" about the patent landscape and what actually exists in the patent record is widening with each training cycle. A landscape query that a general-purpose model partially answered in 2023 may return less useful information in 2026.
3.3 General-Purpose Models Lack Ontological Frameworks for Patent Analysis
A freedom-to-operate analysis is not a summarization task. It requires understanding claim scope, prosecution history, continuation and divisional chains, assignee normalization (a single company may appear under multiple entity names across patent records), priority dates versus filing dates versus publication dates, and the relationship between dependent and independent claims. It requires mapping the specific technical features of a proposed product against independent claim language—not keyword matching.
General-purpose models do not have these frameworks. They pattern-match against training data and produce outputs that adopt the format and tone of patent analysis without the underlying data infrastructure. The format is correct. The confidence is high. The coverage is incomplete in ways that are not visible to the user.
4. Comparative Output Quality
The following table summarizes the qualitative characteristics of each tool's response across the dimensions most relevant to an operational IP workflow.
5. Implications for R&D and IP Organizations
5.1 The Confidence Problem
The central risk identified by this study is not that general-purpose models produce bad outputs—it is that they produce incomplete outputs with high confidence. Each model delivered its results in a professional format with structured analysis, risk ratings, and strategic recommendations. At no point did any model indicate the boundaries of its knowledge or flag that its results represented a fraction of the available patent record. A practitioner receiving one of these outputs would have no signal that the analysis was incomplete unless they independently validated it against a comprehensive datasource.
This creates an asymmetric risk profile: the better the format and tone of the output, the less likely the user is to question its completeness. In a corporate environment where AI outputs are increasingly treated as first-pass analysis, this dynamic incentivizes under-investigation at precisely the moment when thoroughness is most critical.
5.2 The Diversification Illusion
It might be assumed that running the same query through multiple general-purpose models provides validation through diversity of sources. This study suggests otherwise. While the four tools returned different subsets of patents, all operated under the same structural constraints: training data rather than live patent databases, web-scraped content rather than structured IP records, and general-purpose reasoning rather than patent-specific ontological frameworks. Running the same query through three constrained tools does not produce triangulation; it produces three partial views of the same incomplete picture.
5.3 The Appropriate Use Boundary
General-purpose language models are effective tools for a wide range of tasks: drafting communications, summarizing documents, generating code, and exploratory research. The finding of this study is not that these tools lack value but that their value boundary does not extend to decisions that carry existential commercial risk.
Patent landscape analysis, freedom-to-operate assessment, and competitive intelligence that informs R&D investment decisions fall outside that boundary. These are workflows where the completeness and verifiability of the underlying data are not merely desirable but are the primary determinant of whether the analysis has value. A patent landscape that captures 10% of the relevant filings, regardless of how well-formatted or confidently presented, is a liability rather than an asset.
6. Test 2: Competitive Intelligence — Bio-Based Polyamide Patent Landscape
To assess whether the findings from Test 1 were specific to a single technology domain or reflected a broader structural pattern, a second query was submitted to all four tools. This query shifted from freedom-to-operate analysis to competitive intelligence, asking each tool to identify the top 10organizations by patent filing volume in bio-based polyamide synthesis from castor oil derivatives over the past three years, with summaries of technical approach, co-assignee relationships, and portfolio trajectory.
6.1 Query

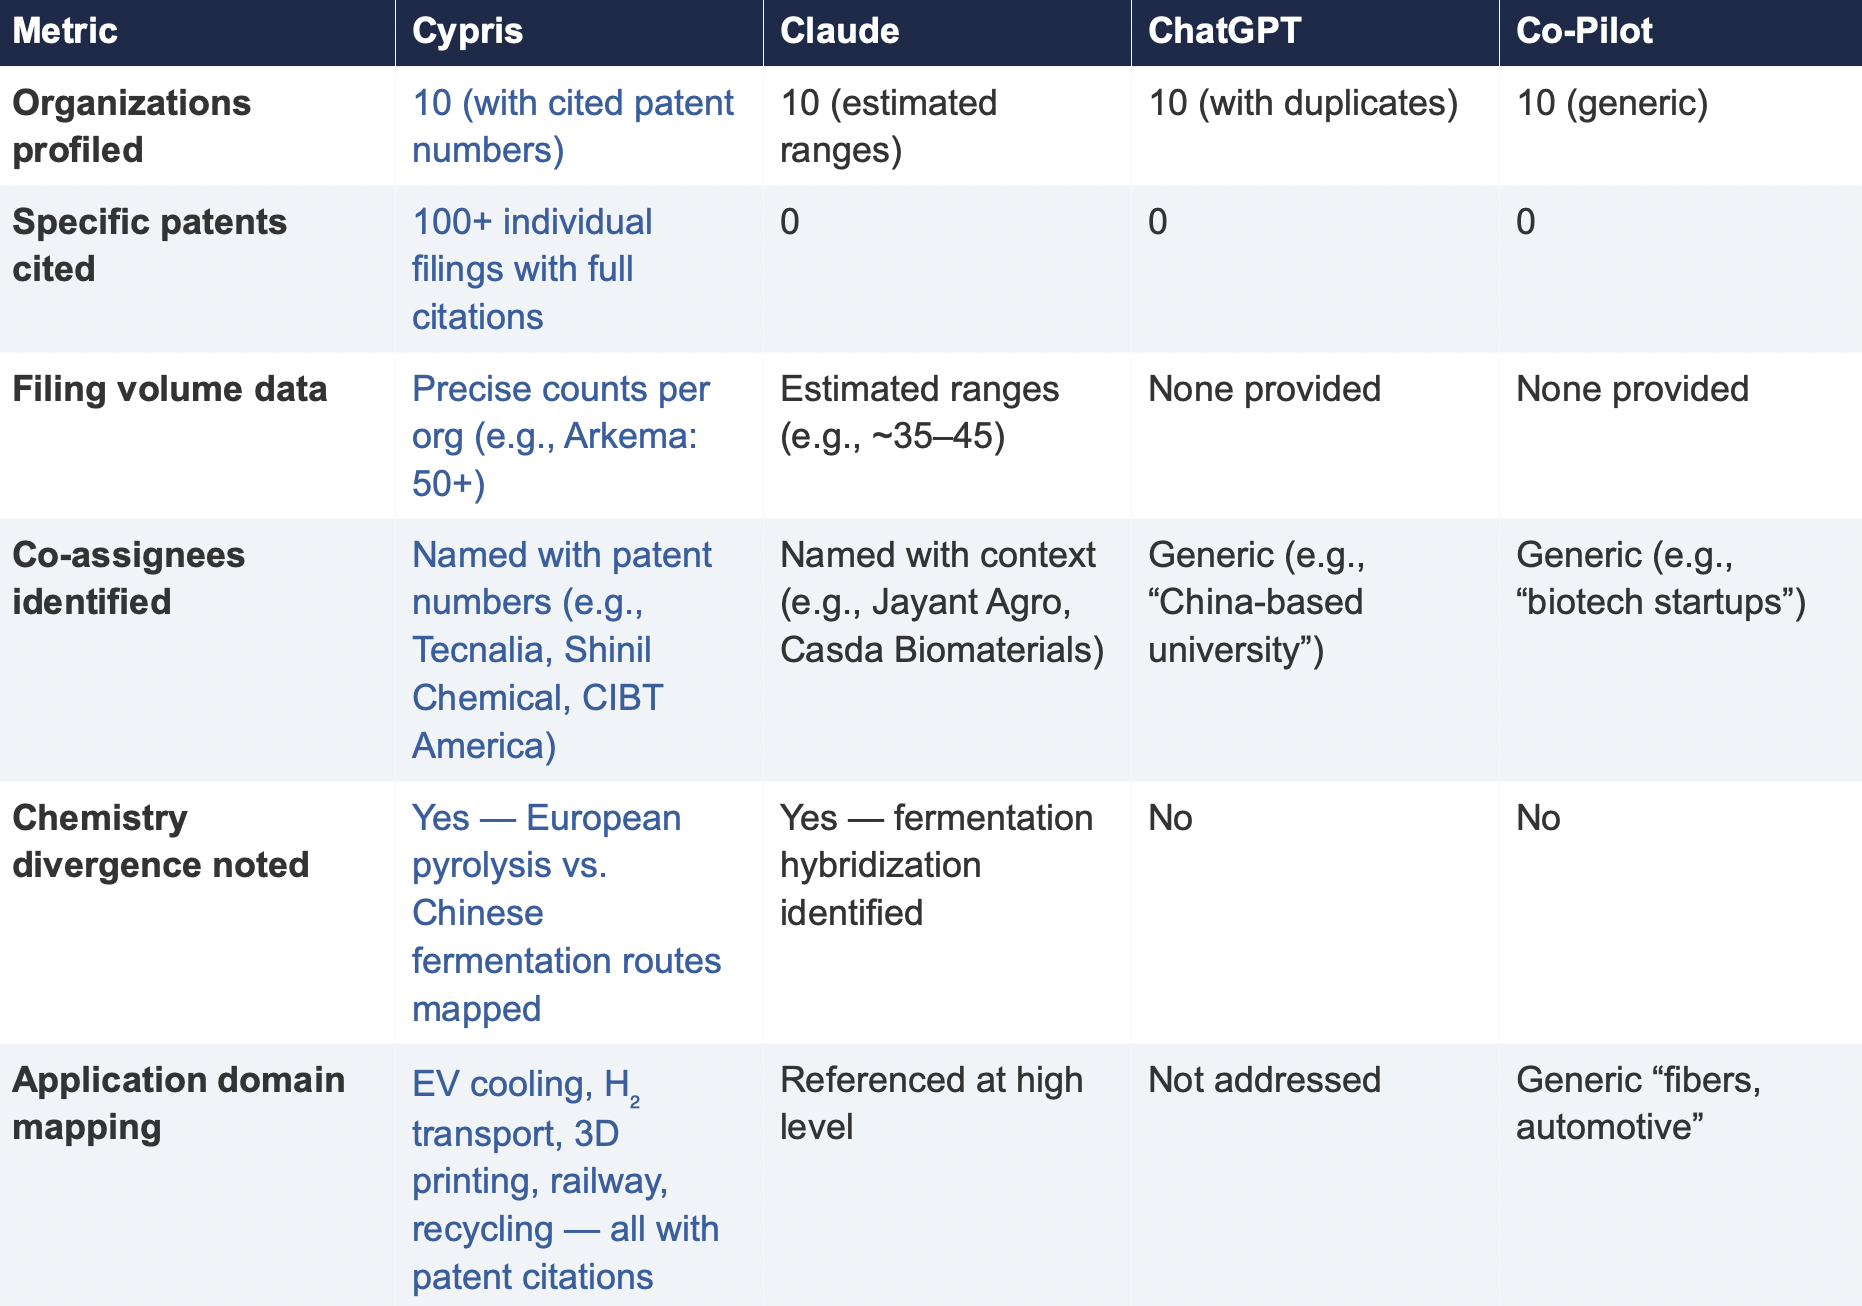
6.2 Summary of Results
6.3 Key Differentiators
Verifiability
The most consequential difference in Test 2 was the presence or absence of verifiable evidence. Cypris cited over 100 individual patent filings with full patent numbers, assignee names, and publication dates. Every claim about an organization’s technical focus, co-assignee relationships, and filing trajectory was anchored to specific documents that a practitioner could independently verify in USPTO, Espacenet, or WIPO PATENT SCOPE. No general-purpose model cited a single patent number. Claude produced the most structured and analytically useful output among the public models, with estimated filing ranges, product names, and strategic observations that were directionally plausible. However, without underlying patent citations, every claim in the response requires independent verification before it can inform a business decision. ChatGPT and Co-Pilot offered thinner profiles with no filing counts and no patent-level specificity.
Data Integrity
ChatGPT’s response contained a structural error that would mislead a practitioner: it listed CathayBiotech as organization #5 and then listed “Cathay Affiliate Cluster” as a separate organization at #9, effectively double-counting a single entity. It repeated this pattern with Toray at #4 and “Toray(Additional Programs)” at #10. In a competitive intelligence context where the ranking itself is the deliverable, this kind of error distorts the landscape and could lead to misallocation of competitive monitoring resources.
Organizations Missed
Cypris identified Kingfa Sci. & Tech. (8–10 filings with a differentiated furan diacid-based polyamide platform) and Zhejiang NHU (4–6 filings focused on continuous polymerization process technology)as emerging players that no general-purpose model surfaced. Both represent potential competitive threats or partnership opportunities that would be invisible to a team relying on public AI tools.Conversely, ChatGPT included organizations such as ANTA and Jiangsu Taiji that appear to be downstream users rather than significant patent filers in synthesis, suggesting the model was conflating commercial activity with IP activity.
Strategic Depth
Cypris’s cross-cutting observations identified a fundamental chemistry divergence in the landscape:European incumbents (Arkema, Evonik, EMS) rely on traditional castor oil pyrolysis to 11-aminoundecanoic acid or sebacic acid, while Chinese entrants (Cathay Biotech, Kingfa) are developing alternative bio-based routes through fermentation and furandicarboxylic acid chemistry.This represents a potential long-term disruption to the castor oil supply chain dependency thatWestern players have built their IP strategies around. Claude identified a similar theme at a higher level of abstraction. Neither ChatGPT nor Co-Pilot noted the divergence.
6.4 Test 2 Conclusion
Test 2 confirms that the coverage and verifiability gaps observed in Test 1 are not domain-specific.In a competitive intelligence context—where the deliverable is a ranked landscape of organizationalIP activity—the same structural limitations apply. General-purpose models can produce plausible-looking top-10 lists with reasonable organizational names, but they cannot anchor those lists to verifiable patent data, they cannot provide precise filing volumes, and they cannot identify emerging players whose patent activity is visible in structured databases but absent from the web-scraped content that general-purpose models rely on.
7. Conclusion
This comparative analysis, spanning two distinct technology domains and two distinct analytical workflows—freedom-to-operate assessment and competitive intelligence—demonstrates that the gap between purpose-built R&D intelligence platforms and general-purpose language models is not marginal, not domain-specific, and not transient. It is structural and consequential.
In Test 1 (LLZO garnet electrolytes for Li-S batteries), the purpose-built platform identified more than three times as many patents as the best-performing general-purpose model and ten times as many as the lowest-performing one. Among the patents identified exclusively by the purpose-built platform were filings rated as Very High FTO risk that directly claim the proposed technology architecture. InTest 2 (bio-based polyamide competitive landscape), the purpose-built platform cited over 100individual patent filings to substantiate its organizational rankings; no general-purpose model cited as ingle patent number.
The structural drivers of this gap—reliance on training data rather than live patent feeds, the accelerating closure of web content to AI scrapers, and the absence of patent-specific analytical frameworks—are not transient. They are inherent to the architecture of general-purpose models and will persist regardless of increases in model capability or training data volume.
For R&D and IP leaders, the practical implication is clear: general-purpose AI tools should be used for general-purpose tasks. Patent intelligence, competitive landscaping, and freedom-to-operate analysis require purpose-built systems with direct access to structured patent data, domain-specific analytical frameworks, and the ability to surface what a general-purpose model cannot—not because it chooses not to, but because it structurally cannot access the data.
The question for every organization making R&D investment decisions today is whether the tools informing those decisions have access to the evidence base those decisions require. This study suggests that for the majority of general-purpose AI tools currently in use, the answer is no.
Study Disclosure
This comparative evaluation was commissioned and published by Cypris. The testing methodology, prompts, evaluation criteria, and underlying outputs have been documented to support independent review and replication.
All platform outputs were preserved in their original form. Patent data and material factual claims were cross-checked against USPTO Patent Center and WIPO PATENTSCOPE records as of March 27, 2026. Cypris was one of the platforms evaluated and therefore has a commercial interest in the findings.
The Patent Intelligence Gap - A Comparative Analysis of Verticalized AI-Patent Tools vs. General-Purpose Language Models for R&D Decision-Making
Blogs
Green ammonia has become a priority for industrial decarbonization, and its patent landscape is distinctive because low-carbon ammonia is being pursued through several competing routes, each with its own chemistry and process engineering. Ammonia is one of the highest-volume chemicals made, the foundation of nitrogen fertilizer, and a candidate hydrogen carrier and fuel, and its conventional production, reforming fossil methane for hydrogen and combining it with nitrogen in the high-temperature, high-pressure Haber-Bosch process, is carbon-intensive: the International Energy Agency attributes to ammonia production roughly 1.3 percent of energy-system carbon dioxide emissions and about 2 percent of total final energy consumption, with direct carbon dioxide emissions on the order of 450 million tonnes a year.¹ Decarbonizing it is therefore a climate priority, and the routes divide into distinct regions of patenting: renewable-powered Haber-Bosch, which replaces fossil hydrogen with hydrogen from water electrolysis and feeds a modified synthesis loop;⁴ direct electrochemical nitrogen reduction, which converts nitrogen to ammonia electrochemically under mild conditions;²,⁵ plasma-electrocatalysis; nitrogen-oxide reduction; and solid-oxide electrochemical cells. Cutting across the routes are the catalysts, the electrode and cell designs, and the process control that adapts synthesis to variable renewable power. Because a competitive process depends on several of these, freedom-to-operate and white space analysis must span the routes and the layers together.
The landscape is being pulled forward by decarbonization and by the sheer scale of demand, so even incremental efficiency and emission gains are valuable. The routes sit at very different stages: renewable-powered Haber-Bosch is the most commercially mature and holds the largest share of patent activity, with established engineering firms filing on integrating intermittent hydrogen supply, buffer storage, and dynamic synthesis-loop control, while direct electrochemical, plasma, and solid-oxide routes are earlier, advancing rapidly in catalyst design and device operation but still facing fundamental efficiency and selectivity limits. Theoretical analysis places the maximum energy efficiency of the leading lithium-mediated electrochemical process at roughly 28 percent, and scaling relations among reaction intermediates constrain how selective nitrogen-to-ammonia catalysts can be, which is why catalyst design is the central research problem for these routes.³,⁷ This shows in the record: across the Cypris corpus of more than 500 million patents and scientific papers, the green and electrochemical ammonia set holds on the order of 3,613 families and grew from about 155 in 2020 to roughly 523 in 2024, with the most active assignees led by established ammonia-technology licensors such as Topsoe and Casale alongside energy majors, and China well ahead of the United States and Denmark on geography; 2025 and 2026 counts are partial because of the publication lag.
The strategic question is which route and layer to back, and the white space sits where the chemistry is hardest. In renewable-powered Haber-Bosch, the open ground is in dynamic operation and process integration that let a plant follow variable renewable power. In the electrochemical routes, catalysts that raise ammonia yield and suppress the competing hydrogen-evolution reaction are the central problem, and they are comparatively open and high-value.²,⁵ Plasma-electrocatalysis and solid-oxide cells are earlier, less-crowded routes, and modular, decentralized designs are strategically important where distributed fertilizer and fuel production matter.⁶ Reading the landscape by route, catalyst, and process, and tracking both the patents and the underlying catalysis research, is what separates a crowded region from an open one.
Where the green-ammonia white space is
Nitrogen-reduction catalysts. Catalysts that raise ammonia yield and suppress the competing hydrogen-evolution reaction are the central problem for the electrochemical route and a comparatively open, high-value layer.²,⁵
Dynamic, flexible Haber-Bosch. Process control and loop designs that let a synthesis plant follow variable renewable power are a large, active layer in the most mature route.⁴
Plasma-electrocatalysis and solid-oxide cells. These earlier routes, including intermediate-temperature solid-oxide electrochemical cells, are less crowded and offer differentiated positions.
Nitrogen-oxide-mediated routes. Pathways that route through nitrogen-oxide intermediates are an emerging, distinct area of chemistry.
Modular, decentralized systems. Small-scale, modular ammonia production near renewable resources and demand is a strategically important system layer.⁶
How AI-powered landscape and white space analysis helps
Resolving a landscape that spans several synthesis routes, each with its own catalysts and process, requires more than keyword search. AI-powered analysis addresses this with semantic search that clusters activity by route, catalyst, and process across varied terminology, attribution that normalizes engineering-firm, startup, and academic filers to canonical entities, and continuous monitoring that keeps pace with a decarbonization-driven surge. Because ammonia-synthesis advances appear in scientific and catalysis literature before they are patented, reading both patents and literature gives the earliest signal of where scalable routes are emerging.
Where Cypris fits
Cypris runs patent landscape and white space analysis for multi-route chemical fields such as green ammonia across a corpus of more than 500 million patents and scientific papers, organized through a proprietary R&D ontology. The ontology clusters activity by route, renewable Haber-Bosch, electrochemical nitrogen reduction, plasma, nitrogen-oxide, and solid-oxide, and by layer, catalyst, cell and electrode, and process control, and normalizes engineering-firm, startup, and academic filers to canonical entities, so a team can resolve which routes and layers are crowded and which remain open as white space, and can track new entrants as the field scales. Semantic search across patents and scientific literature connects filings to the underlying catalysis research, which is where green-ammonia advances appear first. Cypris Q, the platform's agentic layer, lets teams run landscape and white space analysis conversationally and chain the clustering, attribution, and gap analysis, and Agentic Monitoring tracks a defined route over time and flags new patents and papers as they publish. Cypris provides enterprise API partnerships with OpenAI, Anthropic, and Google, and is built with enterprise-grade security. Cypris serves hundreds of enterprise customers across pharmaceuticals, chemicals, advanced materials, energy, and other regulated industries.
FAQ
What is the green ammonia patent landscape? The green ammonia patent landscape is the set of patents covering low-carbon ammonia production. It divides across competing routes, renewable-powered Haber-Bosch, direct electrochemical nitrogen reduction, plasma-electrocatalysis, nitrogen-oxide reduction, and solid-oxide electrochemical cells, each with distinct catalysts and process IP. Each route is a distinct region of patenting.
Why is green ammonia a decarbonization priority? Green ammonia is a decarbonization priority because ammonia is one of the largest-volume chemicals, the backbone of fertilizer, and a candidate fuel and hydrogen carrier, while its conventional production is fossil-fuel-based. The International Energy Agency attributes to it roughly 1.3 percent of energy-system carbon dioxide emissions and about 2 percent of final energy use. Decarbonizing it addresses both food and energy systems.
What routes does the green-ammonia landscape cover? The landscape covers renewable-powered Haber-Bosch, direct electrochemical nitrogen reduction, plasma-electrocatalysis, nitrogen-oxide reduction, and solid-oxide electrochemical cells. Each uses different chemistry and sits at a different maturity, with renewable Haber-Bosch the most commercially advanced. Freedom-to-operate and white space analysis must treat them separately.
Where is the white space in green ammonia? The white space includes nitrogen-reduction catalysts, dynamic and flexible Haber-Bosch operation, plasma-electrocatalysis and solid-oxide cells, nitrogen-oxide-mediated routes, and modular decentralized systems. Renewable Haber-Bosch is comparatively mature and holds the most patents. The most open, high-value opportunities are in electrochemical catalysts and the earlier routes.
Why are nitrogen-reduction catalysts so important? Nitrogen-reduction catalysts are important because the direct electrochemical route's viability depends on raising ammonia yield while suppressing the competing hydrogen-evolution reaction, which otherwise dominates, and because scaling relations among intermediates limit selectivity. Solving this is the central technical problem for that route. The catalyst compositions and cell designs that achieve it are foundational and defensible.
Why does green-ammonia analysis need scientific literature? Green-ammonia analysis needs scientific literature because catalyst and cell advances appear in chemistry research before they are patented, so the literature gives the earliest signal. Analyzing patents alone gives a lagging view. Cypris analyzes both across more than 500 million patents and scientific papers.
What software helps analyze the green ammonia patent landscape? Software for the green-ammonia landscape should cluster activity by route and process layer, resolve engineering-firm, startup, and academic filers to canonical owners, search patents and scientific literature semantically, and monitor a decarbonization-driven field continuously. Cypris does this across more than 500 million patents and scientific papers using a proprietary R&D ontology, semantic search, Cypris Q, and Agentic Monitoring.
Which teams use green ammonia patent landscape analysis? Green ammonia patent landscape analysis is used by R&D, innovation, IP, and strategy teams at chemical, fertilizer, energy, and engineering companies, catalysis developers, and their partners, as well as investors and policymakers. It informs which route to back, where to file, and where competitors are concentrated. Cypris serves hundreds of enterprise customers across chemicals, energy, advanced materials, and other regulated industries.
Endnotes
- International Energy Agency (2021). Ammonia Technology Roadmap. https://www.iea.org/reports/ammonia-technology-roadmap
- Li, S., et al. (2021). Electrochemical ammonia synthesis: mechanistic understanding and catalyst design. Chem, 7(12). https://doi.org/10.1016/j.chempr.2021.01.009
- Fu, X., Zhou, Y., Nørskov, J. K., & Chorkendorff, I. (2024). Electrochemical ammonia synthesis: the energy efficiency challenge. ACS Energy Letters, 9(12). https://doi.org/10.1021/acsenergylett.4c02954
- Gu, Y., et al. (2024). Ambient electrochemical ammonia synthesis: from theoretical guidance to catalyst design. Advanced Science, 11. https://doi.org/10.1002/advs.202308979
- Sankannavar, A., & Shetty, A. (2024). Exploring nitrogen reduction reaction mechanisms in electrochemical ammonia synthesis: a comprehensive review. Journal of Energy Chemistry, 92. https://doi.org/10.1016/j.jechem.2024.01.024
- Chebrolu, V. T., et al. (2023). Overview of emerging catalytic materials for electrochemical green ammonia synthesis. Carbon Energy, 5. https://doi.org/10.1002/cey2.361
- Tsai, C., Vojvodić, A., Montoya, J., & Nørskov, J. K. (2015). The challenge of electrochemical ammonia synthesis: nitrogen scaling relations. ChemSusChem, 8(13). https://doi.org/10.1002/cssc.201500322
The solid-state battery race is being decided at the electrolyte, and the patent landscape divides along three chemistries: sulfide, oxide, and polymer. A solid-state battery replaces the liquid electrolyte of a conventional lithium-ion cell with a solid one, which can improve safety and enable higher-energy electrode pairings. The central engineering problem is that no single solid electrolyte class simultaneously optimizes the three properties that matter, room-temperature ionic conductivity, stability at the electrode interfaces, and manufacturability, so each class represents a different set of trade-offs and a different region of the patent landscape. Understanding where filing activity concentrates by class, and where it does not, is how R&D and IP teams locate defensible positions in one of the fastest-moving areas of energy patenting.
The scale of that activity is documented in primary data. A joint analysis by the European Patent Office and the International Energy Agency found that international patent families in electricity storage grew from 1,029 in 2000 to more than 7,000 in 2018, at an average of 14 percent per year between 2005 and 2018, roughly four times the economy-wide average.¹ Within that, solid-state lithium-ion filings grew faster still, at around 25 percent per year since 2010, reaching 211 international patent families in 2018, with Japan the dominant country of origin, and solid-state electrolyte activity rose several-fold over the decade.¹ More recent analysis reports that energy storage now accounts for roughly 40 percent of all energy-related patenting, confirming that the field has continued to accelerate.² Because applications publish about eighteen months after filing, the most recent activity is under-represented, so these figures understate the current state.
The three electrolyte classes occupy distinct positions defined by their physics. Sulfide electrolytes reach the highest room-temperature ionic conductivities, on the order of 10 to the minus two siemens per centimeter, comparable to or exceeding liquid electrolytes, but they are chemically and electrochemically unstable at the electrode interfaces and sensitive to moisture, so the dominant patenting and research effort targets interfacial stabilization and dry-processing manufacture.³,⁴ Oxide electrolytes, principally garnet-type structures, offer good stability and a wide electrochemical window with intermediate conductivity, typically in the 10 to the minus four to 10 to the minus three siemens per centimeter range, but they are hard and brittle, which makes achieving low-resistance interfaces and scalable, thin, dense layers the central challenge.⁵ Polymer electrolytes are the most manufacturable, compatible with existing roll-to-roll processing, but historically suffered from low room-temperature conductivity, on the order of 10 to the minus seven siemens per centimeter for early systems, though engineered solid polymer electrolytes have since reached the milli-siemens-per-centimeter range, which is why manufacturability arguments increasingly favor them despite the historical conductivity gap.⁶
What the three classes trade off
Sulfide. Highest ionic conductivity, comparable to liquid electrolytes, but poor interfacial and moisture stability; patenting concentrates on interface engineering and dry manufacturing.³
Oxide. Good stability and a wide electrochemical window with intermediate conductivity, but brittleness and interfacial resistance dominate the technical and patenting effort.⁵
Polymer. Best manufacturability and compatibility with existing processes, historically limited by low room-temperature conductivity that engineered systems are now closing.⁶
Emerging classes. Halide and composite electrolytes are an active newer area that combines properties across classes, and the interfacial-engineering literature increasingly treats all classes together.⁷
How to analyze the electrolyte landscape and find white space
Scope the analysis by electrolyte class and by the property being improved, since sulfide, oxide, and polymer activity concentrate on different problems and should be assessed separately.
Aggregate to the patent-family level and attribute to organizations, so international coverage is not double-counted and activity is correctly assigned by country and assignee.
Map patents against the underlying materials research, because solid-electrolyte advances appear in scientific literature before they are patented, so literature coverage gives the earliest signal.
Identify dense and sparse regions within each class, distinguishing crowded problems, such as sulfide interface stabilization, from open white space, such as specific composite or processing approaches.
Correct for publication lag and monitor continuously, since the most recent activity is under-represented and the field moves quickly.
Where Cypris fits
Cypris runs patent landscape and white space analysis for fast-moving fields such as solid-state batteries across a corpus of more than 500 million patents and scientific papers, organized through a proprietary R&D ontology. The ontology clusters activity by electrolyte class and by the property being improved, and normalizes organizations to canonical entities, so a team can resolve which classes and problems are crowded and which remain open as white space. Semantic search across patents and scientific literature connects filings to the underlying materials research, which matters in solid-state batteries because advances appear in the literature before they are patented. Cypris Q, the platform's agentic layer, lets teams run landscape and white space analysis conversationally and chain the class-level scoping, attribution, and gap analysis, and Agentic Monitoring tracks a defined chemistry over time and flags new patents and papers as they publish, which is essential where recent activity is under-represented by publication lag. Cypris provides enterprise API partnerships with OpenAI, Anthropic, and Google, and is built with enterprise-grade security. Cypris serves hundreds of enterprise customers across pharmaceuticals, chemicals, advanced materials, energy, and other regulated industries.
FAQ
What are the three main solid-state battery electrolyte classes?
The three main solid-state battery electrolyte classes are sulfide, oxide, and polymer. They trade off room-temperature ionic conductivity, stability at the electrode interfaces, and manufacturability, and no single class optimizes all three. Each occupies a distinct region of the patent landscape, with halide and composite electrolytes an emerging fourth area.
How do sulfide, oxide, and polymer electrolytes compare?
Sulfide electrolytes have the highest ionic conductivity, around 10 to the minus two siemens per centimeter, but poor interfacial and moisture stability. Oxide garnets offer good stability with intermediate conductivity but are brittle. Polymers are the most manufacturable but historically had low conductivity, which engineered systems are now improving.
How fast is solid-state battery patenting growing?
Solid-state battery patenting is growing quickly. Electricity-storage international patent families grew about 14 percent per year from 2005 to 2018, four times the economy-wide average, and solid-state lithium-ion filings grew around 25 percent per year since 2010. Energy storage now accounts for roughly 40 percent of all energy-related patenting.
Why does ionic conductivity differ so much between electrolyte classes?
Ionic conductivity differs between electrolyte classes because it is governed by the material's structure and ion-transport mechanism. Sulfides allow fast ion movement and reach conductivities comparable to liquids, oxides are intermediate, and polymers historically conducted far more slowly at room temperature. Engineering has narrowed the polymer gap substantially.
Which electrolyte class is winning?
No electrolyte class has decisively won, because each optimizes different properties. Sulfides lead on conductivity, oxides on stability, and polymers on manufacturability, and patenting concentrates on each class's specific weakness. The manufacturability advantage of polymers and the conductivity of sulfides are both driving heavy activity, with the outcome still open.
How do you find white space in the solid-state electrolyte landscape?
Finding white space in the solid-state electrolyte landscape means scoping by class and by the property being improved, mapping patents and scientific literature, and identifying the sparse regions within each class. Because advances appear in research first, literature coverage gives early signal. The white space is where a specific composition or processing approach is viable but few patents yet exist.
Why does solid-state battery analysis need scientific literature?
Solid-state battery analysis needs scientific literature because electrolyte and interface advances appear in materials research before they are patented, so the literature gives the earliest signal of a viable approach. Analyzing patents alone gives a lagging view. Cypris analyzes both across more than 500 million patents and scientific papers.
Why does publication lag matter in the battery patent landscape?
Publication lag matters because applications publish about eighteen months after filing, so the most recent solid-state activity is under-represented in current data. In a field growing this quickly, the latest figures understate the true state. Longer-window trends and continuous monitoring are more reliable.
Who uses solid-state battery patent landscape analysis?
Solid-state battery patent landscape analysis is used by R&D, innovation, IP, and strategy teams at battery makers, automotive and energy companies, materials developers, and their partners. It informs which electrolyte class to pursue, where to file, and where competitors are concentrated. Cypris serves hundreds of enterprise customers across energy, advanced materials, chemicals, and other regulated industries.
Endnotes
- International Energy Agency & European Patent Office (2020). Innovation in Batteries and Electricity Storage: A Global Analysis Based on Patent Data. https://www.iea.org/reports/innovation-in-batteries-and-electricity-storage
- International Energy Agency (2026). The State of Energy Innovation 2026. https://www.iea.org/reports/the-state-of-energy-innovation-2026
- Richter, F. H. et al. (2020). Interfacial challenges for all-solid-state batteries based on sulfide solid electrolytes. Journal of Materiomics. https://doi.org/10.1016/j.jmat.2020.09.003
- Gamo, H., Nagai, A. & Matsuda, A. (2023). Toward Scalable Liquid-Phase Synthesis of Sulfide Solid Electrolytes for All-Solid-State Batteries. Batteries. https://doi.org/10.3390/batteries9070355
- Wei, Z. et al. (2024). Oxide Solid Electrolytes in Solid-State Batteries. Batteries & Supercaps. https://doi.org/10.1002/batt.202400667
- Wei, Z., Guo, R., Li, C. & Peng, H. (2025). Why Will Polymers Win the Race for Solid-State Batteries? Advanced Science. https://doi.org/10.1002/advs.202510481
- Chae, S. et al. (2026). Interfacial Engineering for Layered Oxide Cathodes in All-Solid-State Batteries. Batteries & Supercaps. https://doi.org/10.1002/batt.70366
Direct lithium extraction has become central to scaling lithium supply, and its patent landscape is distinctive because DLE is not a single technology but a set of competing route families, each with its own materials and mechanism. Conventional brine production concentrates lithium in solar evaporation ponds over many months to years, which is slow, land-intensive, and limited to favorable climates; DLE instead recovers lithium selectively from brine using engineered materials, which is faster, has a smaller footprint, and can tap lower-grade and unconventional brines. National-laboratory work classifies the field into five route families, each a distinct region of patenting: adsorption, which captures lithium on aluminum-based or other sorbents; ion exchange, which uses manganese- or titanium-based ion-sieve sorbents and can work on lower-grade brines; solvent extraction; membrane separation; and electrochemical methods.¹,²,³,⁴,⁷ Cutting across the routes are the sorbent and membrane materials, the brine pretreatment that removes hardness and competing ions such as magnesium, the regeneration chemistry, and the conversion of recovered lithium into battery-grade hydroxide or carbonate. Because a commercial process depends on several of these layers, freedom-to-operate and white space analysis must span the routes and the supporting steps together.
The landscape is being pulled forward by demand and by resource economics. Lithium sits at the center of battery supply chains: world reserves are on the order of 30 million tonnes, identified resources are far larger, world mine production reached roughly 240,000 tonnes in 2024, up about eighteen percent on the prior year, and batteries account for the large majority of end use.⁸ Brine resources are a major share of the total and are distributed across countries including those of the lithium triangle, so technologies that unlock them efficiently carry strategic value, and interest has extended from classic salar brines to geothermal and oilfield brines that pair lithium recovery with existing fluid infrastructure.² The route families sit at different stages: adsorption is the most commercially proven, operating at scale in several regions; ion exchange is advancing with developers targeting lower-grade brines;³ and solvent extraction, membrane, and electrochemical routes are earlier, at pilot and demonstration scale, though recent work has shown electrochemical recovery from dilute and high-impurity brines.⁵,⁶ Because applications publish about eighteen months after filing, the most recent sorbent and electrochemical filings are under-represented (2025 and 2026 counts are partial), so the current frontier is more active than granted-patent counts suggest.
The strategic question is which route and layer to back, and the white space sits where selectivity, durability, and cost are hardest. Sorbent and membrane materials with high lithium selectivity, long cycle life, and low regeneration cost are the central materials problem, so composition and process innovation carry high, defensible value.²,³ The earlier routes, membrane and electrochemical, are less crowded and offer room for differentiated positions,⁵,⁶ and technologies that handle lower-grade and unconventional brines, that cut water and energy use, and that integrate recovery with conversion to battery-grade chemicals are all strategically important. Across the Cypris corpus, DLE families number on the order of 1,679 and step up sharply from 2023, with the most active assignees concentrated in China, led by battery-materials and salt-lake specialists alongside oilfield-services filers, and China well ahead of the United States and Canada on geography; these are Cypris-corpus figures, with 2025 and 2026 partial. Reading the landscape by route, material, and step, and tracking both the patents and the underlying separations research, is what separates a crowded region from an open one.
Where the DLE white space is
High-selectivity, durable sorbents. Sorbent and ion-sieve materials with high lithium selectivity, long cycle life, and low-cost regeneration are the central materials problem and a high-value layer.²,³
Membrane and electrochemical routes. The earlier membrane and electrochemical route families are less crowded and offer room for differentiated positions.⁵,⁶
Lower-grade and unconventional brines. Technologies that recover lithium from geothermal and oilfield brines and from low-concentration resources broaden where DLE can be deployed.⁶
Water and energy reduction. Processes that cut the water and energy needed for extraction and regeneration are a differentiating capability under environmental scrutiny.
Integrated conversion to battery-grade chemicals. Recovering lithium and converting it directly to high-purity hydroxide or carbonate is where product value and economics are decided.
How AI-powered landscape and white space analysis helps
Resolving a landscape that spans five route families and several supporting steps requires more than keyword search. AI-powered analysis addresses this with semantic search that clusters activity by route, material, and step across varied terminology, attribution that normalizes developer, resource-company, and academic filers to canonical entities, and continuous monitoring that keeps pace with a demand-driven surge. Because DLE advances appear in scientific and separations literature before they are patented, reading both patents and literature gives the earliest signal of where viable, low-cost routes are emerging.
Where Cypris fits
Cypris runs patent landscape and white space analysis for multi-route materials fields such as direct lithium extraction across a corpus of more than 500 million patents and scientific papers, organized through a proprietary R&D ontology. The ontology clusters activity by route family, adsorption, ion exchange, solvent extraction, membrane, and electrochemical, and by layer, sorbent and membrane materials, pretreatment, regeneration, and conversion, and normalizes developer, resource-company, and academic filers to canonical entities, so a team can resolve which routes and layers are crowded and which remain open as white space, and can track new entrants as the field scales. Semantic search across patents and scientific literature connects filings to the underlying separations and materials research, which is where DLE advances appear first. Cypris Q, the platform's agentic layer, lets teams run landscape and white space analysis conversationally and chain the clustering, attribution, and gap analysis, and Agentic Monitoring tracks a defined route over time and flags new patents and papers as they publish. Cypris provides enterprise API partnerships with OpenAI, Anthropic, and Google, and is built with enterprise-grade security. Cypris serves hundreds of enterprise customers across pharmaceuticals, chemicals, advanced materials, energy, and other regulated industries.
FAQ
What is direct lithium extraction? Direct lithium extraction is a set of technologies that recover lithium selectively from brine using engineered materials, rather than concentrating it in solar evaporation ponds over months to years. It is faster, has a smaller footprint, and can tap lower-grade and unconventional brines. It is central to scaling lithium supply for batteries.
What route families does the DLE landscape cover? The landscape covers five route families: adsorption, ion exchange, solvent extraction, membrane separation, and electrochemical methods. Each uses different materials and mechanisms and sits at a different maturity, with adsorption the most commercially proven. Freedom-to-operate and white space analysis must treat them separately.
Why is DLE strategically important? DLE is strategically important because brine resources hold a large share of global lithium and unlocking them efficiently expands supply for batteries, which account for the large majority of lithium end use. DLE also enables recovery from geothermal and oilfield brines that pair with existing infrastructure. That makes the enabling materials and processes valuable.
Where is the white space in DLE? The white space includes high-selectivity, durable sorbents, the earlier membrane and electrochemical routes, lower-grade and unconventional brines, water and energy reduction, and integrated conversion to battery-grade chemicals. Adsorption is comparatively crowded and proven. The most open, high-value opportunities are in advanced materials and the earlier routes.
Why are sorbent materials the key layer? Sorbent materials are the key layer because the selectivity, cycle life, and regeneration cost of the sorbent largely determine whether a DLE process is efficient and economical. Improving these properties is the central materials problem across adsorption and ion-exchange routes. The composition and process methods that achieve it are foundational and defensible.
Why does DLE analysis need scientific literature? DLE analysis needs scientific literature because sorbent, membrane, and separations advances appear in research before they are patented, so the literature gives the earliest signal. Analyzing patents alone gives a lagging view. Cypris analyzes both across more than 500 million patents and scientific papers.
What software helps analyze the direct lithium extraction patent landscape? Software for the DLE landscape should cluster activity by route family and process layer, resolve developer, resource-company, and academic filers to canonical owners, search patents and scientific literature semantically, and monitor a demand-driven field continuously. Cypris does this across more than 500 million patents and scientific papers using a proprietary R&D ontology, semantic search, Cypris Q, and Agentic Monitoring.
Which teams use DLE patent landscape analysis? DLE patent landscape analysis is used by R&D, innovation, IP, and strategy teams at lithium producers, materials and chemicals companies, energy and resource firms, and their partners, as well as investors and policymakers. It informs which route to back, where to file, and where competitors are concentrated. Cypris serves hundreds of enterprise customers across advanced materials, chemicals, energy, and other regulated industries.
Endnotes
- Stringfellow, W. T., & Dobson, P. F. (2021). Technology for the recovery of lithium from geothermal brines. Energies, 14(20), 6805. https://doi.org/10.3390/en14206805
- Kolb, T., et al. (2022). Lithium extraction techniques and the application potential of different sorbents for lithium recovery from brines. Mineral Processing and Extractive Metallurgy Review. https://doi.org/10.1080/08827508.2022.2047041
- Chen, L., et al. (2024). Advanced lithium ion-sieves for sustainable lithium recovery from brines. Sustainability Horizons. https://doi.org/10.1016/j.horiz.2024.100093
- Razmjou, A., et al. (2024). Lithium recovery from brines. Nature Sustainability, 7. https://doi.org/10.1038/s41893-024-01451-2
- Leones, R. (2024). Membraneless electrochemical extraction of lithium from brines. Nature Chemical Engineering, 1. https://doi.org/10.1038/s44286-024-00155-w
- Zhou, X., et al. (2024). Lithium extraction from low-quality brines. Nature, 634. https://doi.org/10.1038/s41586-024-08117-1
- Hu, J., et al. (2019). Recovery of lithium from salt-lake brines using solvent extraction with TBP and FeCl3. Hydrometallurgy, 189. https://doi.org/10.1016/j.hydromet.2019.105244
- U.S. Geological Survey (2025). Lithium. In Mineral Commodity Summaries 2025. https://doi.org/10.3133/mcs2025


Webinars
Many enterprises have adopted horizontal, foundation-model AI platforms. But access to the same underlying models does not, by itself, create differentiated intelligence. For highly technical and mission-critical research, general-purpose models may produce broad but weakly grounded answers when they lack access to authoritative technical data, specialized context, and verifiable sources.
The next competitive advantage will come from the intelligence layer surrounding the foundation model: the domain-specific data, ontologies, retrieval capabilities, agent workflows, and source grounding that together form an AI harness. These verticalized systems can transform general-purpose AI into a more specialized capability for research, innovation, and technical decision-making.
Join Steve Hafif, Co-Founder and CEO of Cypris.ai, and Marlene Valderrama, Principal IP Manager and Senior Technology Scout at Halliburton, for a conversation on the state of enterprise AI and how organizations can enhance horizontal AI platforms with verticalized intelligence designed for R&D and innovation.


Most IP organizations are making high-stakes capital allocation decisions with incomplete visibility – relying primarily on patent data as a proxy for innovation. That approach is not optimal. Patents alone cannot reveal technology trajectories, capital flows, or commercial viability.
A more effective model requires integrating patents with scientific literature, grant funding, market activity, and competitive intelligence. This means that for a complete picture, IP and R&D teams need infrastructure that connects fragmented data into a unified, decision-ready intelligence layer.
AI is accelerating that shift. The value is no longer simply in retrieving documents faster; it’s in extracting signal from noise. Modern AI systems can contextualize disparate datasets, identify patterns, and generate strategic narratives – transforming raw information into actionable insight.
Join us on Thursday, April 23, at 12 PM ET for a discussion on how unified AI platforms are redefining decision-making across IP and R&D teams. Moderated by Gene Quinn, panelists Marlene Valderrama and Amir Achourie will examine how integrating technical, scientific, and market data collapses traditional silos – enabling more aligned strategy, sharper investment decisions, and measurable business impact.
Register here: https://ipwatchdog.com/cypris-april-23-2026/

In this session, we break down how AI is reshaping the R&D lifecycle, from faster discovery to more informed decision-making. See how an intelligence layer approach enables teams to move beyond fragmented tools toward a unified, scalable system for innovation.
