Insights on Innovation, R&D, and IP
Perspectives on patents, scientific research, emerging technologies, and the strategies shaping modern R&D
Michael Devon, a retired Research Fellow who spent 34 years at Dow tested three AI systems against complex, known-answer R&D scenarios. The largest performance gap appeared where technical depth, IP interpretation and roadmap development mattered most.
General-purpose AI tools such as Microsoft Copilot and Claude Opus 5 are built primarily around frontier foundation models and broad-access knowledge. Cypris can use the same class of foundation models, but grounds them in focused scientific and intellectual property datasets connected through domain-specific ontologies.
This comparison was designed to test whether that additional intelligence layer materially changes the quality of technical research.
Michael Devon, a retired Research Fellow who spent 34 years at Dow, evaluated Cypris, Microsoft Copilot and Claude Opus 5 across two technical scenarios and four prompts. He deliberately chose areas he knew intimately, allowing him to distinguish a plausible summary from an analysis that captured the technical realities, historical context and commercial considerations required to build an R&D strategy.
The scenarios were representative of projects that historically required weeks of coordinated researcher effort. The objective was not simply to determine which tool could find relevant information. It was to determine which could transform that information into useful technical and strategic guidance rooted in real world context.
Evaluation design
The comparison covered two technology landscapes: hollow latex particle opacifiers and the use of hydroxypropyl methylcellulose, or HPMC, in osmotic drug-delivery systems. The outputs were evaluated based on result quality, strategic insight, accuracy and the ability to recognize the boundaries between related technologies.
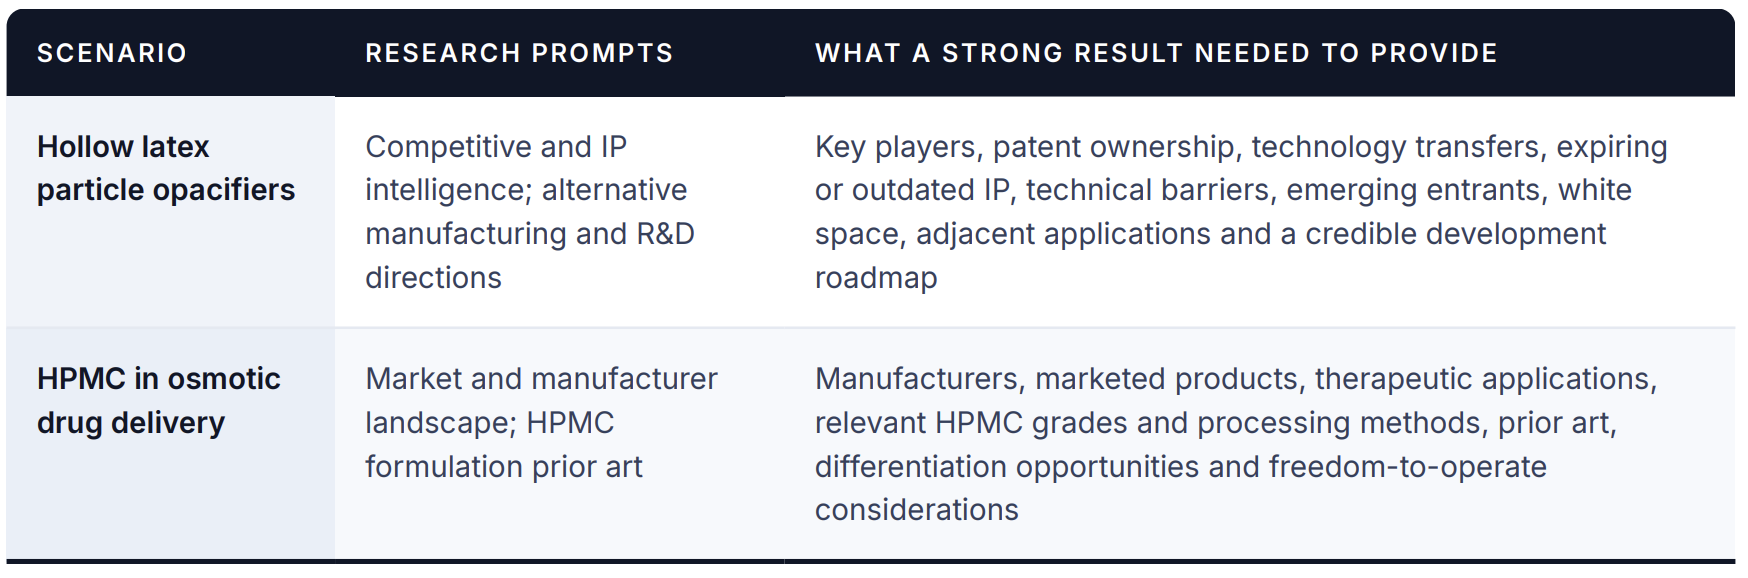
The hollow particle prompts asked the systems to map the competitive and IP landscape, identify emerging participants in Mexico and Asia, detect licensing or corporate activity and locate white space. They were then asked to recommend alternative materials, particle architectures and manufacturing mechanisms that could support a defensible product strategy.
The osmotic delivery prompts asked the systems to identify manufacturers and marketed products, followed by an analysis of HPMC grades, viscosity specifications, processing methods, prior art and potential formulation strategies.
Where the tools diverged
All three tools were capable of producing a credible general summary. The meaningful differences appeared as the work moved from describing the landscape to deciding what to do next.
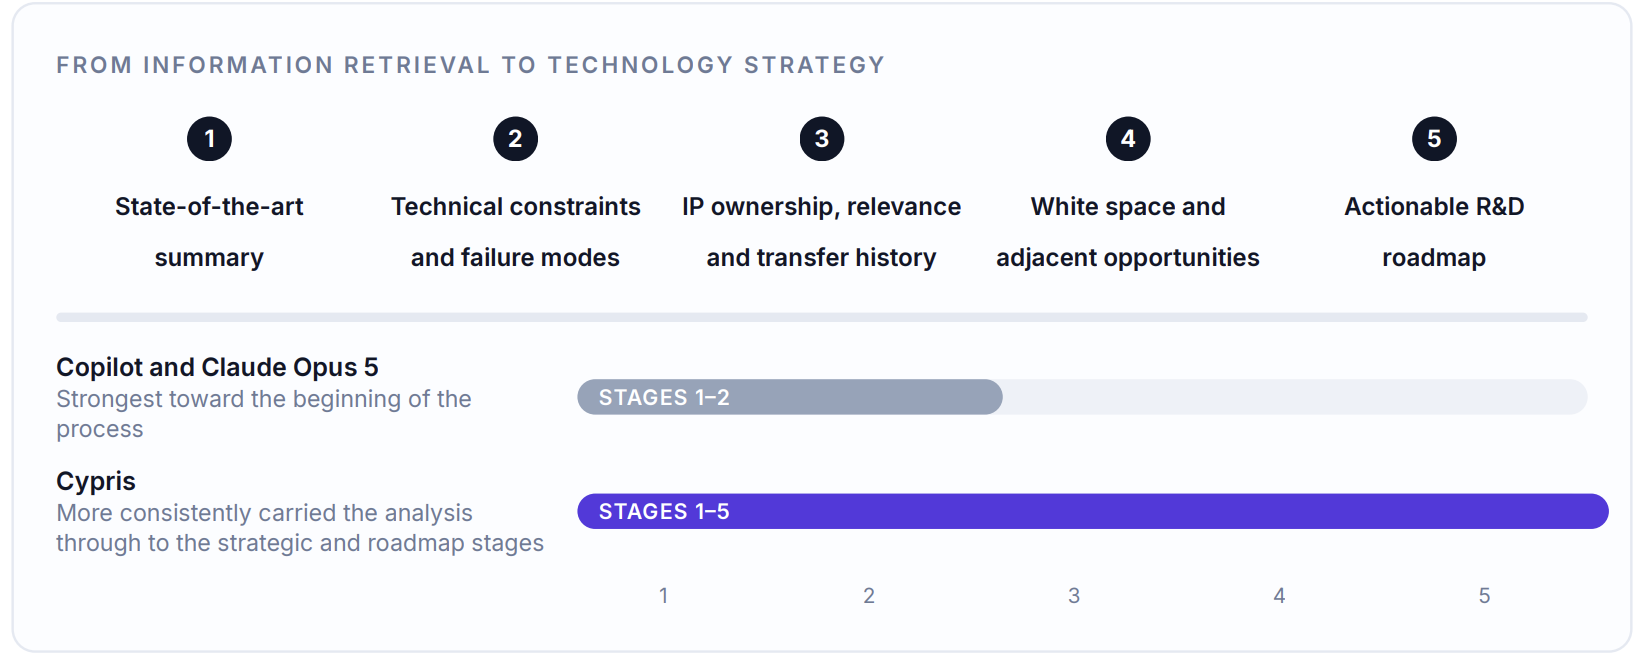
Devon found that Cypris produced the strongest overall result, with the clearest advantage in the more technically and strategically complex hollow particle scenario. Claude and Copilot generally summarized what had been published. Cypris more frequently identified the specific technical issues, changes in IP ownership, commercial signals and research directions that could influence an actual development program.
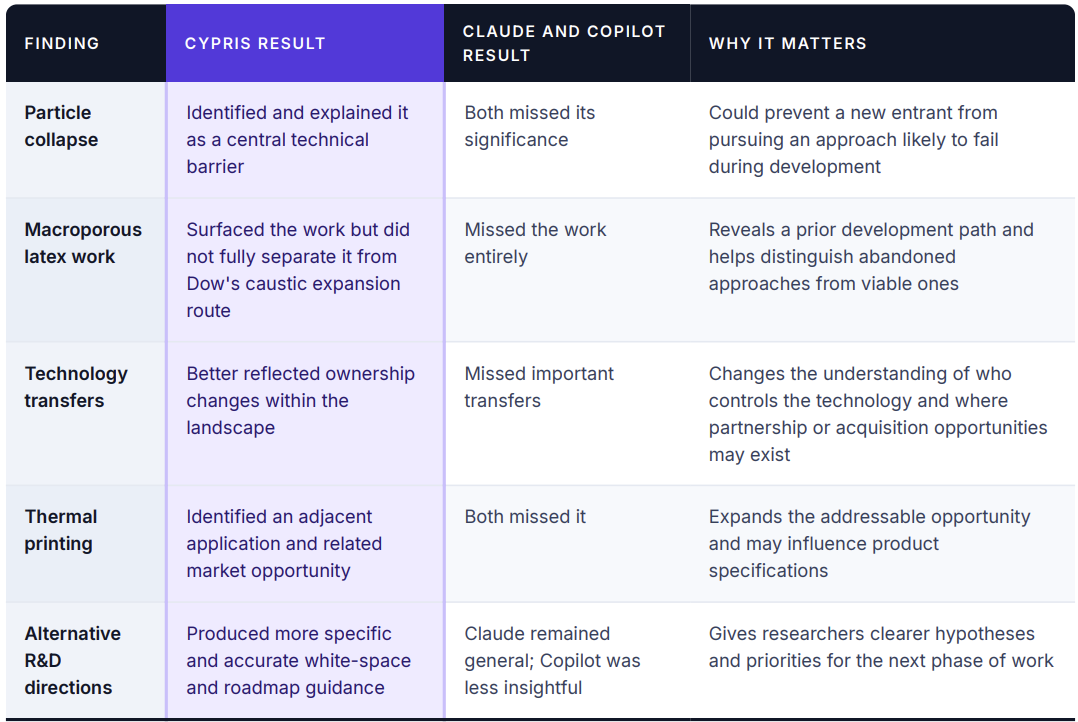
Comparative findings at a glance
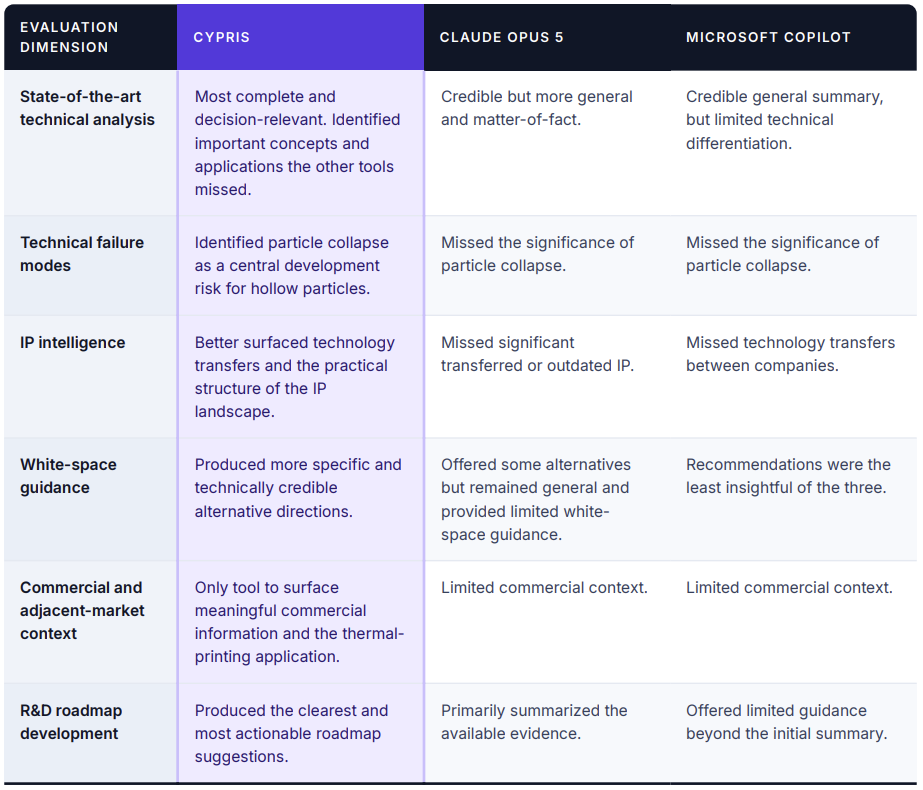
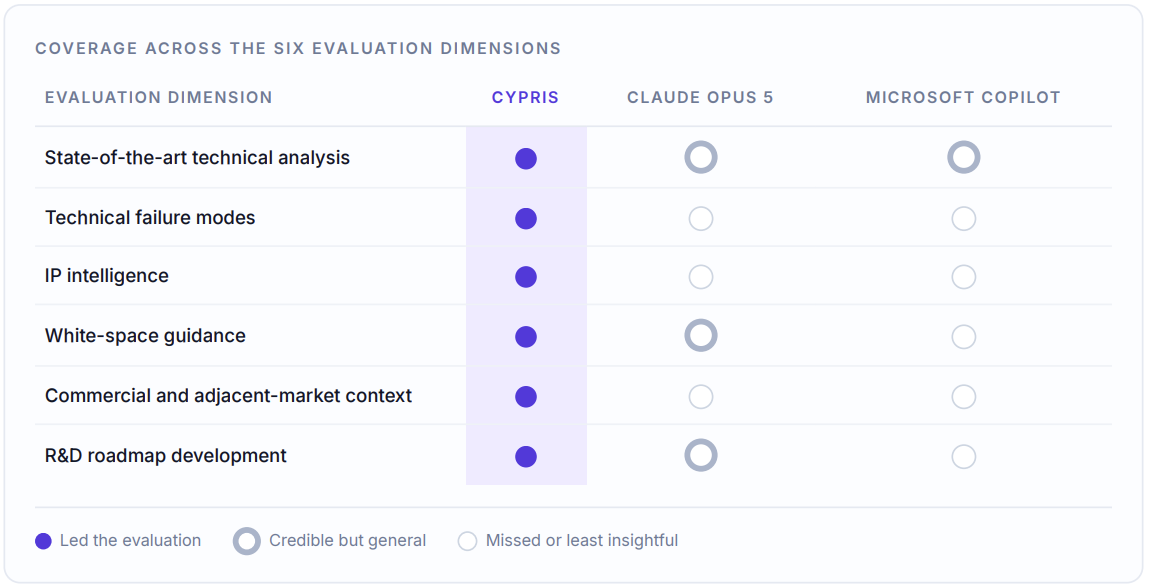
These distinctions were particularly visible in Devon's analysis of technical implementation, IP transfers, market context and research direction.
Scenario One: Hollow Latex Particle Opacifiers
All three tools passed the baseline test
Each system produced a reasonable summary of the general hollow particle landscape. Devon found no serious factual errors within the information each tool chose to present.
That baseline performance was important, but it did not determine the outcome. The systems differed substantially in the usefulness of their output for technical strategy development, with Cypris holding the clear advantage.
Cypris identified the technical issue most likely to derail a new entrant
One of the most consequential differences involved particle collapse.
Cypris recognized that maintaining particle structure was a central technical challenge and produced a useful explanation of the issue. Claude and Copilot did not identify its importance.
For a researcher, this was not a minor omission. A new entrant that fails to understand or overcome particle collapse could invest considerable time and capital in a manufacturing approach that does not perform under practical conditions. By surfacing the issue, Cypris provided information that could directly alter experimental priorities and development sequencing.
Cypris was not flawless. It did not fully distinguish between Dow's hollow latex work using caustic expansion and a separate abandoned macroporous latex approach. However, Claude and Copilot missed the macroporous work entirely.
The distinction illustrates the difference between partial technical interpretation and simple omission. Cypris found the relevant body of work but needed greater precision in separating the approaches. The general AI tools failed to surface the alternative development path at all.
Cypris produced a stronger picture of the IP landscape
Patent landscapes are often presented as lists of companies, filings and portfolio sizes. For technology strategy, that is rarely sufficient.
Researchers need to understand whether patents remain active and relevant, whether they have been transferred, whether the underlying technology is commercially practiced and whether a seemingly large portfolio contains meaningful gaps.
Claude and Copilot missed technology transfers between companies. Devon also found that Claude failed to recognize that significant portions of the IP landscape had changed hands or become outdated. These omissions can distort the competitive picture by assigning technology to the wrong owner or treating historically important patents as if they still define the current opportunity.
Cypris provided a more useful view of how the IP was structured and where potential white space existed. This helped move the analysis beyond a patent count and toward questions such as:
- Who currently controls the relevant technology?
- Which patents still create meaningful barriers?
- Where has ownership changed?
- Which approaches appear abandoned or underdeveloped?
- Where could a new entrant build, partner or acquire?
Devon noted that all three tools could be improved by incorporating deeper patent-office and file-wrapper information, maintenance status, litigation history and citation patterns. Those signals help determine whether a portfolio is genuinely defensible or simply appears strong based on volume.
Cypris surfaced technical and commercial concepts the others missed
Cypris was the only tool to identify the use of hollow particles in thermal printing. It also suggested additional markets and alternative applications.
That finding demonstrated a broader advantage in state-of-the-art analysis. Cypris did not restrict the output to the most obvious use of hollow particles as opacifiers. It connected the underlying technology to another commercially relevant application that Claude and Copilot failed to identify.
The distinction matters because technical strategy requires answering two different questions:
- Can the organization develop the technology?
- Is the opportunity commercially worth pursuing?
Claude and Copilot largely addressed the first question through general technical summaries. Cypris brought in more of the information required to begin addressing the second.
Some commercial outputs still required scrutiny. Devon considered Cypris' estimated 10 percent compound annual growth rate for the broader hollow particle market questionable, although its approximately 5 percent estimate for the thermal-printing segment appeared reasonable. The advantage was not that every market figure was definitive. It was that Cypris recognized adjacent commercial applications and incorporated them into the strategic analysis at all.
Cypris produced more useful white-space and roadmap recommendations
Both Cypris and Claude suggested alternatives to conventional latex-based particle systems. Copilot's recommendations were less insightful.
The quality of the alternatives, however, was different. Claude's output was more general and matter-of-fact. It identified possible approaches but did not translate them into strong white-space guidance.
Cypris proposed more technically credible alternatives and connected them more directly to a differentiated development strategy. Its roadmap recommendations were clearer about which directions merited further investigation and how the research could be sequenced.
The alternatives included non-latex and ceramic-based particle systems. The evaluation did not establish that every proposed direction was commercially viable, but Devon knew that some ceramic particles had progressed at least as far as commercial trials. Cypris therefore surfaced technically relevant research leads rather than merely generating hypothetical possibilities.
Specific findings that changed the strategic value of the output
Scenario Two: HPMC in Osmotic Drug Delivery
The baseline outputs were more similar
The osmotic drug-delivery scenario produced less separation between the three systems.
All three generated credible summaries of osmotic pump technology and identified, to varying degrees, the grades and functions of HPMC in the existing landscape. Devon found relatively little to distinguish the tools on the initial market, manufacturer and prior-art questions.
The systems also converged on a similar roadmap recommendation: use a Design of Experiments process to optimize HPMC for the different roles it plays in the formulation.
While technically valid, Devon considered that recommendation underwhelming. It represented a standard development methodology rather than a differentiated technical insight.
Cypris generated the most promising next research direction
The difference appeared when Cypris suggested a possible connection between osmotic delivery and the challenge of formulating poorly soluble drugs.
Many active pharmaceutical ingredients have limited aqueous solubility, creating substantial formulation and absorption challenges. Cypris' analysis pointed toward a possible connection with hydroxypropyl methylcellulose acetate succinate, or HPMCAS, a material used in approaches for poorly soluble drugs.
HPMCAS is distinct from the HPMC traditionally used in osmotic systems, and Cypris did not present the connection as a validated solution. Instead, it surfaced a cross-domain clue that an experienced researcher could recognize and investigate further.
Devon viewed this as a meaningful example of how technical research often progresses. The first search does not always deliver the final answer. A strong research system should also reveal the next productive question.
Cypris did that more effectively. It connected information from an adjacent technical area to the osmotic formulation problem, creating the basis for a more differentiated next prompt and potential research direction.
The Core Finding: Technical Intelligence Begins Where the Summary Ends
The comparison showed that general-purpose AI tools can produce useful technical summaries. Both Claude Opus 5 and Microsoft Copilot identified relevant companies, scientific concepts and prior art across the two scenarios.
Cypris separated itself in the work that followed:
- Recognizing a technical failure mode that could derail a development program
- Identifying ownership changes and outdated IP that altered the competitive landscape
- Finding adjacent applications such as thermal printing
- Producing more specific white-space guidance
- Connecting evidence to a clearer R&D roadmap
- Generating cross-domain clues that informed the next research question
This distinction reflects the role of the intelligence layer surrounding the foundation model. A general-purpose model is optimized to explain the available information coherently. A technical intelligence system must also organize patents, scientific literature, companies, materials and market signals into a structure that supports decisions.
Final assessment
Across the four prompts, Cypris produced the strongest overall performance.
The advantage was clearest in the hollow particle scenario, where Cypris demonstrated superior technical analysis, stronger IP intelligence, more credible white-space identification and more actionable roadmap recommendations. Claude Opus 5 was capable of producing credible summaries and some alternative ideas, but remained more general and missed important IP changes and white-space implications. Microsoft Copilot met the baseline requirement for landscape summarization but provided the least differentiated strategic guidance.
The osmotic delivery scenario was more competitive, but Cypris still produced the most promising next research direction by connecting the problem to an adjacent material and formulation challenge.
The conclusion was not simply that Cypris found more information. It more consistently identified the information that mattered.
For an experienced technical leader, that is the difference between receiving a summary of the landscape and receiving the raw material required to build a technology strategy.
Former Dow Research Fellow Compares Cypris, Copilot & Claude for Chemical Intelligence
All Blogs
Sustainable aviation fuel has moved from pilot projects to a mandated market, and its patent landscape is distinctive because SAF is not a single technology but a set of competing production routes, each with its own feedstocks, catalysts, and process chemistry. Peer-reviewed technical reviews lay out the route taxonomy: the hydroprocessed-ester-and-fatty-acid route converts waste oils and fats into jet fuel and is currently the most mature; the Fischer-Tropsch route gasifies biomass or waste into synthesis gas and rebuilds it into hydrocarbons; the alcohol-to-jet route converts ethanol or other alcohols into jet-range molecules; and the synthetic power-to-liquid route, including methanol-mediated pathways, combines captured carbon dioxide with green hydrogen to make e-fuels with no biological feedstock at all.¹,²,³,⁴,⁷ Because each route is a distinct region of patenting, freedom-to-operate and white space analysis must treat SAF as several landscapes at once, spanning feedstock pretreatment, catalysts, conversion processes, and upgrading.
The landscape is being pulled forward by regulation more directly than most. Under the European Union's ReFuelEU Aviation regulation, the sustainable share of aviation fuel supplied at EU airports rises stepwise to 70 percent by 2050, with a dedicated sub-obligation for synthetic e-fuels and an anti-tankering rule requiring airlines to uplift most of their fuel where they operate; Switzerland adopted the ReFuelEU framework from January 1, 2026.⁹ This creates both a deadline and a guaranteed market against a very large baseline, since global commercial jet-fuel demand is on the order of 100 billion gallons a year and is projected to rise substantially by 2050.¹ The near-term response has concentrated in the waste-oil route because it is the most mature,⁴,⁵ but the mandates specifically favor synthetic e-fuels in the longer term, which is steering research and filings toward the power-to-liquid route and its underlying carbon-conversion and catalysis challenges. The patent record shows this tension clearly: across the Cypris corpus of more than 500 million patents and scientific papers, the SAF space holds roughly 6,000 de-duplicated families and grew about 3.6 times between 2022 and 2024, and on an indicative basis the Fischer-Tropsch and e-fuel routes lead patent activity, ahead of hydroprocessed waste oils, with alcohol-to-jet the smallest slice, even though the waste-oil route currently leads in deployed production capacity, a divergence between where filing and where building are concentrated. The most active assignees span engine makers, refining-and-catalysis licensors, and route pure-plays, and the United States leads on geography, followed by the United Kingdom, China, France, and the Nordic producers. Because applications publish about eighteen months after filing, the most recent catalyst and e-fuel filings are under-represented (2025 and 2026 counts are partial), so the current frontier is more active than granted-patent counts suggest.
The strategic question is which route and layer to back, and the white space sits where cost and feedstock constraints are hardest. The waste-oil route is limited by feedstock availability, so its white space is narrower; the Fischer-Tropsch and alcohol-to-jet routes turn on catalyst performance and process integration;²,³,⁸ and the synthetic e-fuel route, though earliest and most expensive, is the one the mandates most favor and the one with the most open, high-value IP, particularly in the catalysts and process designs that lower the cost of converting carbon dioxide and hydrogen into jet fuel.⁶,⁷ Reading the landscape by route, feedstock, catalyst, and process, and tracking both the patents and the underlying chemistry research, is what separates a crowded region from an open one.
Where the SAF white space is
Synthetic e-fuel catalysis. Catalysts and process designs that lower the cost of converting captured carbon dioxide and green hydrogen into jet-range hydrocarbons are the most favored by mandate and among the most open, high-value targets.⁶,⁷
Alcohol-to-jet conversion. Improved catalysts and process integration for converting alcohols to jet-range molecules are an active, still-developing route.⁸
Fischer-Tropsch from waste and biomass. Gasification, syngas conditioning, and Fischer-Tropsch catalysis for waste and biomass feedstocks are a distinct, contested layer.²,³
Feedstock flexibility and pretreatment. Technologies that broaden or pretreat feedstocks, easing the supply constraint on mature routes, are a differentiated area.⁴
Process intensification and integration. Designs that integrate steps, cut energy use, and lower capital cost are where scale-up economics are decided.⁵
How AI-powered landscape and white space analysis helps
Resolving a landscape that spans several production routes, each with its own feedstocks, catalysts, and processes, under a moving regulatory timeline, requires more than keyword search. AI-powered analysis addresses this with semantic search that clusters activity by route, feedstock, catalyst, and process across varied terminology, attribution that normalizes filers to canonical entities and tracks new entrants, and continuous monitoring that keeps pace with a mandate-driven surge. Because SAF advances appear in scientific and catalysis literature before they are patented, reading both patents and literature gives the earliest signal of where scalable routes are emerging.
Where Cypris fits
Cypris runs patent landscape and white space analysis for multi-route fields such as sustainable aviation fuel across a corpus of more than 500 million patents and scientific papers, organized through a proprietary R&D ontology. The ontology clusters activity by production route, waste-oil, Fischer-Tropsch, alcohol-to-jet, and synthetic e-fuel, and by layer, feedstock, catalyst, conversion, and upgrading, and normalizes filers to canonical entities, so a team can resolve which routes and layers are crowded and which remain open as white space, and can track new entrants as the field scales. Semantic search across patents and scientific literature connects filings to the underlying catalysis and process research, which is where SAF advances appear first. Cypris Q, the platform's agentic layer, lets teams run landscape and white space analysis conversationally and chain the clustering, attribution, and gap analysis, and Agentic Monitoring tracks a defined route over time and flags new patents and papers as they publish. Cypris provides enterprise API partnerships with OpenAI, Anthropic, and Google, and is built with enterprise-grade security. Cypris serves hundreds of enterprise customers across pharmaceuticals, chemicals, advanced materials, energy, and other regulated industries.
FAQ
What is the sustainable aviation fuel patent landscape? The sustainable aviation fuel patent landscape is the set of patents covering the several routes used to make jet fuel with lower lifecycle emissions, including hydroprocessed waste oils, Fischer-Tropsch fuels, alcohol-to-jet, and synthetic power-to-liquid e-fuels. Each route has distinct feedstocks, catalysts, and processes. It is best understood as several landscapes rather than one.
Why is regulation shaping SAF patenting? Regulation shapes SAF patenting because binding blending mandates require a rising share of sustainable aviation fuel over the coming decades, reaching 70 percent by 2050 under the EU ReFuelEU Aviation regulation, with a dedicated sub-mandate for synthetic e-fuels. Near-term activity has concentrated in the mature waste-oil route, while the mandates steer longer-term research toward e-fuels. The patent record tracks this policy pull closely.
What production routes does the SAF landscape cover? The SAF landscape covers hydroprocessed waste oils and fats, Fischer-Tropsch fuels from gasified biomass or waste, alcohol-to-jet conversion, and synthetic power-to-liquid e-fuels made from captured carbon dioxide and green hydrogen. Each is a distinct region of patenting. Freedom-to-operate and white space analysis must treat them separately.
Where is the white space in SAF? The white space sits in synthetic e-fuel catalysis, alcohol-to-jet conversion, Fischer-Tropsch from waste and biomass, feedstock flexibility and pretreatment, and process intensification. The mature waste-oil route is comparatively crowded and feedstock-limited. The most open, high-value opportunities are in the e-fuel catalysts and processes the mandates most favor.
Why is the synthetic e-fuel route strategically important? The synthetic e-fuel route is strategically important because the mandates specifically favor it in the longer term, it has no biological feedstock limit, and it is the least mature and most expensive route, which leaves the most open, high-value IP. The central challenge is lowering the cost of converting carbon dioxide and hydrogen into jet fuel. That is where much of the defensible catalysis and process IP is concentrating.
Why does the patent record differ from deployed capacity in SAF? The patent record differs from deployed capacity because filing tends to run ahead of building. In the Cypris corpus the Fischer-Tropsch and e-fuel routes lead in patent activity, even though the hydroprocessed waste-oil route currently leads in installed production capacity. That divergence signals where developers expect the next phase of growth.
What software helps analyze the sustainable aviation fuel patent landscape? Software for the SAF landscape should cluster activity by production route and process layer, resolve filers to canonical owners, search patents and scientific literature semantically, and monitor a mandate-driven field continuously. Cypris does this across more than 500 million patents and scientific papers using a proprietary R&D ontology, semantic search, Cypris Q, and Agentic Monitoring.
Which teams use SAF patent landscape analysis? SAF patent landscape analysis is used by R&D, innovation, IP, and strategy teams at fuel producers, chemicals and catalysis companies, airlines and energy majors, and their partners, as well as investors and policymakers. It informs which route to back, where to file, and where competitors are concentrated. Cypris serves hundreds of enterprise customers across chemicals, energy, advanced materials, and other regulated industries.
Endnotes
- Heyne, J., Holladay, J., & Abdullah, Z. (2020). Sustainable aviation fuel: review of technical pathways. Pacific Northwest National Laboratory / U.S. Department of Energy, Bioenergy Technologies Office. https://doi.org/10.2172/1660415
- Zhang, X., Zheng, Y., Li, J., & Wang, X. (2025). Research advances and future perspectives in Fischer-Tropsch synthesis for sustainable aviation fuel. Sustainable Energy & Fuels. https://doi.org/10.1039/d5se01412c
- Vreugdenhil, B., Boymans, E., Viar, H., et al. (2025). Syngas to sustainable aviation fuel: emerging catalysts and routes. Applied Catalysis A: General. https://doi.org/10.1016/j.apcata.2025.120554
- Chang, K., Ng, J., Japar, W. M. A. W., et al. (2026). Lipid feedstocks for sustainable aviation fuel via HEFA: status and challenges. Renewable and Sustainable Energy Reviews. https://doi.org/10.1016/j.rser.2026.117006
- Gómez, J., & Gyandoh, D. (2025). Techno-economic analysis of HEFA and lignocellulosic biomass conversion for sustainable aviation fuel. Applied Energy. https://doi.org/10.1016/j.apenergy.2025.126421
- Riaz, A., Qyyum, M. A., Al-Muhtaseb, A. H., Al-Jahwari, F., & Saeed, A. (2026). Carbon-derived and biomass-based sustainable aviation fuel pathways: a comparative techno-economic and life-cycle review for aviation decarbonization. Carbon Capture Science & Technology. https://doi.org/10.1016/j.ccst.2026.100641
- Karlsruhe Institute of Technology (2025). Sustainable aviation fuel production via the methanol pathway: a technical review. Sustainable Energy & Fuels. https://doi.org/10.5445/ir/1000187428
- Probabilistic technoeconomic analysis of alcohol-to-jet sustainable aviation fuel: implications for design and decision making (2026). https://doi.org/10.1088/2977-3504/ae7801/v2/review1
- European Commission, Directorate-General for Mobility and Transport. ReFuelEU Aviation. https://transport.ec.europa.eu/transport-modes/air/environment/refueleu-aviation_en
Cellular reprogramming has become one of the most closely watched areas in longevity biotechnology, and its patent landscape is distinctive because the leading approach builds directly on an already foundational technology. Full reprogramming, using the four Yamanaka factors, resets an adult cell all the way to a pluripotent, embryonic-like state; partial or transient reprogramming instead applies a subset of those factors briefly, aiming to roll back the epigenetic state of an aged cell toward a younger profile while preserving its identity and function. In animal models, partial reprogramming has ameliorated age-associated hallmarks and, in one landmark study, restored youthful epigenetic patterns and recovered vision after optic-nerve injury, evidence that framed aging partly as a loss of epigenetic information that reprogramming can help reverse.¹,² Because a rejuvenation therapy is assembled from several independently patentable pieces, the reprogramming-factor set and its ratios, the delivery system, the inducible control mechanism, the target tissue and indication, and the tools used to measure biological age, freedom-to-operate is a multi-layer, multi-owner analysis rather than a single clearance.
The foundational layer shapes everything above it. The original induced-pluripotent-stem-cell reprogramming methods, established through the forced expression of a defined set of transcription factors, sit under a well-known foundational estate that has been broadly licensed,³ and partial-reprogramming approaches inherit questions about how far that foundation reaches. Independent work has shown that epigenetic reprogramming can unlock tissue regenerative potential, reinforcing why these methods are so contested.⁴ This academic origin is visible in the ownership record: across the Cypris corpus of more than 500 million patents and scientific papers, the most active assignees in the cellular-reprogramming and induced-pluripotency space are led by academic and translational institutions, including Kyoto University, the University of California San Diego, the University of Texas System, Memorial Sloan Kettering, and Harvard, alongside cell-therapy companies, and the corpus holds on the order of 28,700 de-duplicated families, with the United States, China, and Japan the leading jurisdictions. Layered on top are newer, fast-growing estates specific to partial and transient reprogramming, cyclic and inducible expression schemes, chemical or small-molecule reprogramming that avoids transcription factors altogether, and tissue-specific delivery. Because applications publish about eighteen months after filing, the most recent reprogramming, delivery, and control filings are under-represented, so the current frontier is more active than granted-patent counts suggest.
The landscape is a well-capitalized race, and the strategic question is which layer to own. In January 2026 the field reached a milestone when the US Food and Drug Administration cleared the first human trial of a partial epigenetic reprogramming therapy, an investigational optic-neuropathy treatment; the clearance authorizes a first-in-human study and is not itself evidence of efficacy.⁹ Across the Cypris corpus, filings in this space grew from a few hundred families per year at the start of the last decade to roughly 3,200 in 2024, with 2025 counts partial because of the publication lag. Several richly funded companies are pursuing different factor sets, delivery routes, and target tissues, and a recurring challenge is to separate genuine rejuvenation, a measured reduction in biological age, from a mere slowing of decline.⁵ The durable value increasingly sits not in the general idea of reprogramming, which rests on the contested foundation, but in the specific, well-supported improvements: safe and controllable expression systems that avoid tumor risk, factor combinations and chemical alternatives, tissue-targeted delivery, and the validated biomarkers, including epigenetic clocks, used to demonstrate rejuvenation.⁶,⁷,⁸ Reading the landscape by layer and by owner, and tracking both the patents and the underlying research, is what separates a workable position from a blocked one.
What creates FTO risk in cellular reprogramming
Foundational reprogramming claims. These cover the underlying induced-pluripotency methods and factor sets, a broadly licensed foundation whose reach into partial approaches shapes everything above it.
Partial and inducible-control claims. These cover transient, cyclic, and inducible expression schemes that rejuvenate without full dedifferentiation, a fast-growing and contested layer.
Delivery claims. These cover viral vectors, lipid nanoparticles, and mRNA delivery of reprogramming factors, a distinct and separately owned layer often decisive for a therapy.
Chemical and small-molecule reprogramming claims. These cover approaches that induce rejuvenation without transcription factors, an emerging and less-crowded route.
Target, indication, and biomarker claims. These cover specific tissues and indications and the epigenetic-age measurements used to demonstrate effect, so a platform can be free for one application and blocked for another.
How AI-powered landscape and FTO analysis helps
A multi-layer, multi-owner landscape built on a contested foundation is beyond manual clearance. AI-powered analysis addresses this with semantic search that retrieves relevant foundational, partial-reprogramming, delivery, control, and target claims regardless of terminology, attribution that resolves academic and commercial owners to canonical entities and captures the license and spinout chains, claim-level analysis that separates the layers, and continuous monitoring that tracks new filings and the fast-moving research. Because reprogramming advances appear in scientific literature well before they are patented, reading both patents and literature gives the earliest warning of where the field is heading.
Where Cypris fits
Cypris runs patent landscape and freedom-to-operate analysis for multi-layer, academically rooted fields such as cellular reprogramming across a corpus of more than 500 million patents and scientific papers, organized through a proprietary R&D ontology. The ontology clusters the landscape by layer, foundational reprogramming, partial and inducible control, delivery, chemical reprogramming, and target and biomarker, and normalizes academic and commercial owners to canonical entities, so a team can trace how rights and licenses are distributed across many parties rather than read a flat list. Semantic search across patents and scientific literature surfaces relevant claims regardless of terminology and connects filings to the underlying research, which is where new factor sets, control systems, and delivery methods emerge first. Cypris Q, the platform's agentic layer, lets teams run landscape and FTO analysis conversationally and chain the attribution, clustering, and claim-level analysis across layers, and Agentic Monitoring tracks the landscape over time and flags new filings and developments as they publish. Cypris provides enterprise API partnerships with OpenAI, Anthropic, and Google, and is built with enterprise-grade security. Cypris serves hundreds of enterprise customers across pharmaceuticals, chemicals, advanced materials, energy, and other regulated industries.
FAQ
What is cellular reprogramming in the longevity context? Cellular reprogramming in the longevity context is the use of reprogramming factors to reset the epigenetic state of aged cells toward a younger profile. Partial or transient reprogramming applies a subset of the Yamanaka factors briefly, aiming to rejuvenate cells without erasing their identity. It is being pursued as an approach to age-related disease and tissue restoration.
Why is freedom-to-operate hard for reprogramming therapies? Freedom-to-operate is hard for reprogramming therapies because a therapy is assembled from several independently patentable layers, the reprogramming-factor set, the delivery system, the inducible control mechanism, the target tissue, and biomarker tools, often held by different owners on top of a foundational estate. Clearing one layer does not clear the others. FTO is therefore a multi-layer, multi-owner analysis.
How does the foundational iPSC estate affect partial reprogramming? The foundational induced-pluripotent-stem-cell estate affects partial reprogramming because partial approaches use the same reprogramming factors, so questions about how far the foundation reaches propagate into the newer methods. The foundation has been broadly licensed. Partial-reprogramming developers must consider both the foundation and the specific improvement layers.
What claim types create FTO risk in reprogramming? Five claim types create FTO risk: foundational reprogramming claims, partial and inducible-control claims, delivery claims, chemical and small-molecule reprogramming claims, and target, indication, and biomarker claims. Each covers a distinct layer and can be held by a different owner. Control systems and delivery are especially decisive.
Where is the white space in cellular reprogramming? The white space sits in safe and controllable expression systems that avoid tumor risk, chemical and small-molecule reprogramming, tissue-specific delivery, specific factor combinations, and validated biomarkers of biological age. The general concept rests on a contested foundation. The durable, defensible value is in these specific improvement and delivery layers.
Why does reprogramming analysis need scientific literature? Reprogramming analysis needs scientific literature because new factor sets, control systems, and delivery methods appear in research well before they are patented, so the literature gives the earliest signal in a fast-moving field. Analyzing patents alone gives a lagging view. Cypris analyzes both across more than 500 million patents and scientific papers.
What software helps analyze the cellular reprogramming patent landscape? Software for the cellular reprogramming landscape should resolve academic and commercial owners and license chains to canonical entities, cluster the foundational, control, delivery, and target layers, search patents and scientific literature semantically, and monitor a fast-moving field continuously. Cypris does this across more than 500 million patents and scientific papers using a proprietary R&D ontology, semantic search, Cypris Q, and Agentic Monitoring.
Which teams need reprogramming patent landscape and FTO analysis? Reprogramming patent landscape and FTO analysis is needed by R&D, IP, and business-development teams at longevity and gene-therapy companies, academic technology-transfer offices, and investors assessing rejuvenation assets. The multi-layer, contested landscape makes structured analysis essential. Cypris serves hundreds of enterprise customers across pharmaceuticals and other research-intensive industries.
This article addresses patents and freedom-to-operate and is not legal, medical, or investment advice, and contains no clinical or dosing guidance. FTO determinations should be reviewed with qualified patent counsel.
Endnotes
- Ocampo, A., Reddy, P., Izpisua Belmonte, J. C., et al. (2016). In vivo amelioration of age-associated hallmarks by partial reprogramming. Cell, 167(7). https://doi.org/10.1016/j.cell.2016.11.052
- Lu, Y., Krishnan, A., Sinclair, D. A., et al. (2020). Reprogramming to recover youthful epigenetic information and restore vision. Nature, 588. https://doi.org/10.1038/s41586-020-2975-4
- Takahashi, K., & Yamanaka, S. (2013). Induced pluripotent stem cells in medicine and biology. Development, 140(12). https://doi.org/10.1242/dev.092551
- Reddy, P., Izpisua Belmonte, J. C., & Memczak, S. (2021). Unlocking tissue regenerative potential by epigenetic reprogramming. Cell Stem Cell, 28(3). https://doi.org/10.1016/j.stem.2020.12.006
- Zhang, B., Trapp, A., Kerepesi, C., & Gladyshev, V. N. (2021). Emerging rejuvenation strategies—reducing the biological age. Aging Cell, 21(1). https://doi.org/10.1111/acel.13538
- Moqri, M., Poganik, J. R., Gladyshev, V. N., & Horvath, S. (2025). What makes biological age epigenetic clocks tick. Nature Aging. https://doi.org/10.1038/s43587-025-00833-1
- Mammalian Methylation Consortium; Horvath, S., et al. (2023). Universal DNA methylation age across mammalian tissues. Nature Aging, 3. https://doi.org/10.1038/s43587-023-00462-6
- Ferrucci, L., et al. (2019). Measuring biological aging in humans: a quest. Aging Cell, 19(2). https://doi.org/10.1111/acel.13080
- Life Biosciences (2026, January 28). Life Biosciences announces FDA clearance of IND application for ER-100 in optic neuropathies. https://www.lifebiosciences.com/life-biosciences-announces-fda-clearance-of-ind-application-for-er-100-in-optic-neuropathies
Prior art search for artificial intelligence and machine learning inventions is one of the hardest retrieval problems in patent work, for reasons specific to how AI knowledge is produced and disclosed. Prior art search establishes whether an invention is novel by finding any earlier disclosure that describes it. In most fields, the relevant disclosures are predominantly patents. In AI and machine learning, the most relevant and most recent disclosures are predominantly non-patent literature: preprints on arXiv, proceedings from conferences such as NeurIPS and ICML, open-source code and model documentation, and technical reports. These sources are published quickly and openly, often well ahead of any corresponding patent, so a prior art search confined to patent databases misses the state of the art.
The volume compounds the difficulty. AI scientific publications more than doubled from about 102,000 in 2013 to more than 242,000 in 2023, growing nearly 20 percent in the final year alone.¹ Patenting has grown even faster from a smaller base: AI patents granted worldwide rose from 3,833 in 2010 to 122,511 in 2023, an increase of almost 30 percent in the last year measured.¹ Generative AI illustrates the velocity of the literature most sharply, with related scientific publications rising from 116 in 2014 to more than 34,000 in 2023 while generative-AI patent families grew more than 800 percent over roughly the same period.² A prior art searcher in this field is therefore working against both a large and a rapidly expanding corpus, split across patent and non-patent sources.
Retrieval quality falls exactly where AI prior art needs it most. Patent retrieval is already harder than general-domain information retrieval, and controlled evaluation shows that cross-domain retrieval, finding relevant art outside the query's own technology area, performs several times worse than in-domain retrieval; one recent family-level benchmark found out-of-domain retrieval roughly five times worse than in-domain across hundreds of controlled configurations.³,⁴ AI and machine-learning methods are applied across many application domains, so relevant prior art for an AI invention is frequently located in a different field than the invention's stated use, which is precisely the cross-domain case where conventional retrieval degrades. This is the technical reason keyword and classification search alone are insufficient for AI prior art, and why dense, semantic methods have become the focus of research on patent prior art retrieval.⁵,⁶
Why AI prior art is distinctively hard
Non-patent literature dominates. The most relevant and most recent AI disclosures appear first in preprints, conference proceedings, and open-source code, so a patent-only search misses the state of the art.
Exploding volume. AI publications more than doubled to over 242,000 in 2023, and AI patents granted rose to 122,511, so the corpus a searcher must cover is both large and expanding rapidly.¹
Cross-domain dispersion. AI methods are applied across many fields, so relevant prior art is often in a different technology area than the invention, which is where retrieval degrades most.³
Fast obsolescence of terminology. AI vocabulary evolves quickly, so keyword search misses conceptually identical work described in newer or different terms.
Software-claim breadth. Algorithmic and software claims can be drafted broadly and abstractly, which makes matching a claim to its closest prior art a conceptual rather than a lexical task.
How semantic search closes the gap
Semantic search addresses each of these problems. It retrieves conceptually relevant disclosures regardless of terminology, which handles both fast-evolving vocabulary and broadly drafted software claims. Applied across both patents and scientific literature in one corpus, it covers the non-patent literature where AI prior art concentrates rather than patents alone. And because dense retrieval encodes meaning rather than surface form, it is better positioned than keyword search for the cross-domain case, retrieving relevant art from a different application area than the invention. Combined with an ontology that organizes retrieval by concept, semantic search returns a structured, high-recall view of the prior art rather than a keyword-limited sample.
Where Cypris fits
Cypris runs semantic prior art search across a corpus of more than 500 million patents and scientific papers, organized through a proprietary R&D ontology. Because the corpus spans both patents and scientific literature, Cypris covers the non-patent literature where AI and machine-learning prior art concentrates, rather than patents alone. Semantic search retrieves conceptually relevant disclosures regardless of terminology, which handles the fast-evolving vocabulary and broadly drafted software claims characteristic of AI inventions, and the ontology organizes retrieval by concept so cross-domain prior art in a different application area is surfaced rather than missed. Cypris Q, the platform's agentic layer, lets teams run and chain prior art and novelty analysis conversationally, and Agentic Monitoring tracks a technology area over time so newly published disclosures are surfaced as they appear, which matters in a field moving as fast as AI. Cypris provides enterprise API partnerships with OpenAI, Anthropic, and Google, and is built with enterprise-grade security. Cypris serves hundreds of enterprise customers across pharmaceuticals, chemicals, advanced materials, energy, and other regulated industries.
FAQ
Why is prior art search hard for AI and machine learning inventions?
Prior art search is hard for AI and machine learning inventions because the most relevant and most recent disclosures are predominantly non-patent literature, such as preprints, conference proceedings, and open-source code, which a patent-only search misses. The corpus is also large and expanding rapidly, and AI methods are dispersed across many application domains. These factors make high-recall, cross-domain retrieval essential.
Why does non-patent literature matter so much for AI prior art?
Non-patent literature matters for AI prior art because AI research is published quickly and openly, often well ahead of any corresponding patent, so the state of the art appears first in preprints, conference papers, and code. A search confined to patent databases misses these disclosures. Effective AI prior art search must cover both patents and scientific literature.
How large is the AI prior art corpus?
The AI prior art corpus is large and growing quickly. AI scientific publications more than doubled from about 102,000 in 2013 to over 242,000 in 2023, and AI patents granted worldwide rose from 3,833 in 2010 to 122,511 in 2023. Generative-AI publications alone grew from 116 in 2014 to more than 34,000 in 2023.
What makes AI prior art retrieval technically difficult?
AI prior art retrieval is technically difficult because AI methods are applied across many domains, so relevant prior art is often in a different technology area than the invention, and cross-domain retrieval performs several times worse than in-domain retrieval. One benchmark found out-of-domain retrieval roughly five times worse than in-domain. Fast-evolving terminology and broadly drafted software claims add further difficulty.
Why is keyword search insufficient for AI prior art?
Keyword search is insufficient for AI prior art because AI terminology evolves quickly and software claims are often drafted broadly and abstractly, so conceptually identical work is described in different terms. Keyword search matches surface form and misses these. Semantic search retrieves by meaning, which is what the task requires.
How does semantic search improve AI prior art search?
Semantic search improves AI prior art search by retrieving conceptually relevant disclosures regardless of terminology, across both patents and scientific literature, and by handling the cross-domain case where relevant art is in a different field. It encodes meaning rather than surface form. Combined with an ontology, it returns a structured, high-recall view of the prior art.
Does AI prior art search need to cover scientific literature?
AI prior art search needs to cover scientific literature because the most relevant and most recent AI disclosures appear there first, in preprints, conference proceedings, and technical reports. Covering patents alone leaves the state of the art unretrieved. Cypris searches both across more than 500 million patents and scientific papers.
Which teams run AI prior art search?
AI prior art search is run by IP, R&D, and patent teams at technology companies and across industries adopting AI, as well as by patent professionals assessing novelty. It is increasingly important as AI patenting grows. Cypris serves hundreds of enterprise customers across research-intensive and regulated industries.
How current does AI prior art search need to be?
AI prior art search needs to be continuously current, because AI research and filings publish constantly and the state of the art shifts quickly. A one-time search reflects only the moment it was run. Cypris uses Agentic Monitoring to track a technology area and surface newly published disclosures as they appear.
Endnotes
- Stanford Institute for Human-Centered Artificial Intelligence (2025). Artificial Intelligence Index Report 2025, Chapter 1. arXiv:2504.07139. https://doi.org/10.48550/arxiv.2504.07139
- World Intellectual Property Organization (2024). Patent Landscape Report: Generative Artificial Intelligence. Geneva: WIPO. https://doi.org/10.34667/tind.49740
- Cavallucci, N., Chibane, I. & Ayaou, M. (2026). DAPFAM: A Domain-Aware Family-level Dataset to benchmark cross-domain patent retrieval. Array. https://doi.org/10.1016/j.array.2026.100720
- Lupu, M. (2013). Patent Retrieval. Foundations and Trends in Information Retrieval. https://doi.org/10.1561/1500000027
- Stamatis, V. (2022). End to End Neural Retrieval for Patent Prior Art Search. Lecture Notes in Computer Science. https://doi.org/10.1007/978-3-030-99739-7_66
- Zihayat, M. & Etwaroo, R. (2021). A non-factoid question answering system for prior art search. Expert Systems with Applications. https://doi.org/10.1016/j.eswa.2021.114910
Tightening regulation of per- and polyfluoroalkyl substances is reshaping materials chemistry, and it is opening patent white space for organizations that can develop fluorine-free alternatives. PFAS are used for water, oil, and stain resistance across coatings, textiles, firefighting foams, membranes, semiconductors, and food packaging, and they are now the subject of the broadest chemical restriction ever proposed in Europe. The universal PFAS restriction proposal submitted to the European Chemicals Agency in January 2023 by five national authorities covers on the order of 10,000 substances, and it drew more than 5,600 comments from over 4,400 organizations, an unprecedented response that reflects how many industries are affected.¹ The scope depends on definition: under the 2021 OECD definition, which classifies a substance as PFAS if it contains at least one fully fluorinated carbon, several million catalogued substances qualify, while the number in active commercial use is far smaller.²
The regulatory trajectory is a sequence of tightening actions rather than a single event, which is what makes the resulting innovation demand durable. In the European Union, restrictions moved from PFOS in 2006 to PFOA and related substances in later years, to a PFHxA restriction adopted in 2024, a ban on PFAS in firefighting foams, and a ban on PFAS in food-contact packaging taking effect in 2026, with the universal restriction proposal under scientific evaluation through 2026.¹ In the United States, the Environmental Protection Agency finalized the first national drinking-water limits for several PFAS in 2024, setting maximum contaminant levels of 4.0 parts per trillion for PFOA and PFOS and higher limits for other compounds, and designated PFOA and PFOS as hazardous substances under the federal cleanup statute the same year.³ ECHA has estimated that, absent action, several million tonnes of PFAS would reach the environment over the coming decades.¹
This regulatory pressure is a well-understood driver of innovation. The Porter hypothesis, that well-designed environmental regulation can induce innovation that partly or wholly offsets compliance costs, has been supported across two decades of evidence and a multi-country meta-analysis, and firm-level studies show environmental regulation inducing greener product innovation specifically in chemical industries.⁴,⁵,⁶ For materials developers, the implication is direct: regulation is converting fluorine-free chemistry from a niche into a competitive frontier, and the organizations that build defensible IP positions early will hold advantage as substitution accelerates.
Where the white space is
Firefighting foams. Fluorine-free foams are the most advanced substitution area, driven by bans on PFAS-containing aqueous film-forming foams, though performance and toxicity gaps relative to legacy foams remain an active research and patenting frontier.⁷
Textile and coating treatments. Water- and oil-repellent finishes are a major PFAS use, and fluorine-free hydrophobic and oleophobic coatings, including bio-based and hierarchical-structured approaches, are an active area of development with room for defensible positions.⁸,⁹
Membranes and packaging. Food-contact packaging faces near-term bans, and membrane and barrier applications require substitutes that match performance, which keeps white space open where a fluorine-free chemistry can meet the functional requirement.
Semiconductors and specialty uses. Certain high-performance uses have few current substitutes, so these areas are simultaneously the hardest to displace and the most valuable to solve, and the patent landscape around viable alternatives is comparatively sparse.
How to find PFAS-alternative white space
Scope the application area and functional requirement precisely, since PFAS substitution is application-specific and a fluorine-free chemistry that works for textiles may not work for firefighting foam.
Map patents and scientific literature across the fluorine-free chemistries relevant to that application, because materials research precedes patenting and gives the earliest signal of a viable alternative.
Cluster activity by concept and attribute it to organizations, using an ontology to group related chemistry and normalize assignees, so dense and sparse regions are visible.
Identify the sparse, defensible regions, distinguishing genuine white space from areas that are sparse only because a chemistry does not yet meet the functional requirement.
Monitor continuously, tracking both the chemistry and the regulatory timeline, so filings and restrictions are surfaced as they publish and a white space position is secured before substitution accelerates.
Where Cypris fits
Cypris runs patent landscape and white space analysis for regulation-driven fields such as PFAS alternatives across a corpus of more than 500 million patents and scientific papers, organized through a proprietary R&D ontology. Semantic search across patents and scientific literature surfaces fluorine-free chemistry regardless of nomenclature and connects filings to the underlying materials research, which is where the earliest signals of viable alternatives appear. The ontology clusters activity by application and chemistry and normalizes organizations to canonical entities, so a team can resolve which fluorine-free approaches are crowded and which remain open as white space. Cypris Q, the platform's agentic layer, lets teams run landscape and white space analysis conversationally and chain the search, attribution, and gap analysis, and Agentic Monitoring tracks a defined chemistry over time and flags new filings as they publish. Cypris provides enterprise API partnerships with OpenAI, Anthropic, and Google, and is built with enterprise-grade security. Cypris serves hundreds of enterprise customers across pharmaceuticals, chemicals, advanced materials, energy, and other regulated industries.
FAQ
Why is PFAS regulation creating patent white space?
PFAS regulation is creating patent white space by driving demand for fluorine-free alternatives across many applications, faster than defensible IP positions have been established. The EU REACH universal restriction covers roughly 10,000 substances and US EPA rules now limit several PFAS, so substitution is accelerating. Organizations that build fluorine-free IP early can hold advantage as demand rises.
What is the EU REACH universal PFAS restriction?
The EU REACH universal PFAS restriction is a proposal submitted to the European Chemicals Agency in January 2023 by five national authorities to restrict the manufacture and use of PFAS as a class, covering on the order of 10,000 substances. It drew more than 5,600 comments from over 4,400 organizations. It is under scientific evaluation, with the outcome expected to shape substitution across many industries.
What US rules apply to PFAS?
In the United States, the Environmental Protection Agency finalized the first national drinking-water limits for several PFAS in 2024, setting maximum contaminant levels of 4.0 parts per trillion for PFOA and PFOS and higher limits for other compounds, and designated PFOA and PFOS as hazardous substances under the federal cleanup statute the same year. These actions increase the pressure to substitute PFAS. They apply alongside state-level restrictions.
Which application areas have the most PFAS-alternative white space?
Firefighting foams, textile and coating treatments, membranes and packaging, and certain semiconductor and specialty uses all have PFAS-alternative white space, though the amount varies. Firefighting-foam alternatives are the most advanced, while high-performance specialty uses have few substitutes and are the most valuable to solve. White space is largest where a fluorine-free chemistry can meet the functional requirement but few patents yet exist.
How does regulation drive innovation in materials?
Regulation drives innovation in materials by creating demand for compliant substitutes, a pattern described by the Porter hypothesis and supported by two decades of evidence and firm-level studies in chemical industries. Well-designed regulation induces innovation that can partly offset compliance costs. For PFAS, this is converting fluorine-free chemistry from a niche into a competitive frontier.
How do you find white space in PFAS alternatives?
Finding white space in PFAS alternatives means scoping a specific application and functional requirement, mapping patents and scientific literature across the relevant fluorine-free chemistries, clustering activity by concept, and identifying the sparse, defensible regions. Because materials research precedes patenting, literature coverage gives early signal. The analysis must distinguish genuine white space from areas that are sparse because no chemistry yet meets the requirement.
Why does PFAS-alternative analysis need scientific literature?
PFAS-alternative analysis needs scientific literature because fluorine-free chemistries appear in research before they are patented, so the literature gives the earliest signal of a viable alternative. Analyzing patents alone gives a lagging view. Cypris analyzes both across more than 500 million patents and scientific papers.
Which teams work on PFAS alternatives?
PFAS alternatives are developed by R&D, innovation, and IP teams in chemicals, advanced materials, coatings, textiles, consumer products, and their suppliers, alongside regulatory affairs. The work is driven by tightening regulation and customer demand for fluorine-free products. Cypris serves hundreds of enterprise customers across chemicals, advanced materials, and other regulated industries.
How do you keep a PFAS-alternatives landscape current? Keeping a PFAS-alternatives landscape current requires continuous monitoring of both the chemistry and the regulatory timeline, because filings and restrictions evolve constantly. A one-time landscape ages quickly as new rules and patents publish. Cypris uses Agentic Monitoring to track a defined chemistry over time and flag new filings as they publish.
Endnotes
- European Chemicals Agency. Registry of restriction intentions: per- and polyfluoroalkyl substances (PFAS) universal restriction proposal (2023) and related consultation and evaluation materials. https://echa.europa.eu/
- OECD (2021). Reconciling Terminology of the Universe of Per- and Polyfluoroalkyl Substances: Recommendations and Practical Guidance; and US Environmental Protection Agency PFAS inventory materials.
- US Environmental Protection Agency (2024). PFAS National Primary Drinking Water Regulation; and CERCLA designation of PFOA and PFOS as hazardous substances. https://www.epa.gov/pfas
- Ambec, S., Cohen, M. A., Elgie, S. & Lanoie, P. (2013). The Porter Hypothesis at 20. Review of Environmental Economics and Policy. https://doi.org/10.1093/reep/res016
- Yan, Z., Li, Y., Zhang, X. & Zhu, J. (2024). Revisiting the Porter hypothesis: a multi-country meta-analysis. Humanities and Social Sciences Communications. https://doi.org/10.1057/s41599-024-02671-9
- Choi, J., Kang, J. & Chung, S. (2025). Environmental regulation, induced innovation, and greener transition: firm-level evidence. Journal of Development Economics. https://doi.org/10.1016/j.jdeveco.2025.103678
- Hossain, T., Ormond, R. B. et al. (2024). Exploring the Prospects and Challenges of Fluorine-Free Firefighting Foams (F3) as Alternatives to AFFF: A Review. ACS Omega. https://doi.org/10.1021/acsomega.4c03673
- Likozar, B. et al. (2024). Unveiling PFAS-free Solutions for Hydrophobic and Oleophobic Textile Coatings. https://doi.org/10.55295/psl.2024.i19
- Nicolas, M. et al. (2024). PFAS-free hierarchical superhydrophobic textiles. Advanced Engineering Materials. https://doi.org/10.1002/adem.202401736
Freedom-to-operate for GLP-1 receptor agonists and peptide therapeutics is among the most demanding FTO problems in pharmaceuticals, because protection in this class is built as a dense, layered thicket that extends far beyond the active ingredient. Freedom-to-operate determines whether making, using, or selling a product would infringe another party's active patent claims. In the GLP-1 and peptide space, answering that question requires reading many claim types across many patents, because a single product is protected by a stack of filings covering the molecule, its formulation, its dosing, its delivery device, and its manufacture. A peer-reviewed analysis of GLP-1 receptor agonists approved between 2005 and 2021 found that manufacturers listed a median of 19.5 patents per product, that 54 percent of those patents were on delivery devices rather than the active ingredient, that the median expected protection was 18.3 years after approval, and that no generic manufacturer had yet successfully challenged a GLP-1 receptor agonist patent.¹
The commercial stakes are large. Industry analyst forecasts vary widely with scope, placing the GLP-1 market anywhere from the low tens of billions of dollars to well over one hundred billion by 2030 and projecting double-digit annual growth; these are analyst estimates rather than authoritative figures, and they differ mainly in what they count.² The scale of the opportunity is what drives the density of the patent thicket, because each additional protected feature can delay competition on a high-revenue product. For any organization developing a follow-on peptide, a biosimilar, or a differentiated GLP-1 product, FTO is therefore a gating analysis rather than a formality.
Peptide therapeutics compound the difficulty. Peptides can be claimed as sequences and modifications, formulated for stability and half-life extension, delivered by injection or increasingly by oral routes, and manufactured through distinct synthesis and purification processes, so the claim surface is broad. Recent filing activity has shifted toward oral delivery, dual and triple receptor agonists, and combination therapies, which is where both the newest FTO risk and the remaining white space now sit.³ An FTO analysis in this class has to cover all of these dimensions, and it has to stay current as the frontier moves.
What creates FTO risk in GLP-1 and peptide products
Composition-of-matter claims. These cover the peptide itself, including sequences, analogues, and modifications, and are the primary protection, though in a mature class many core molecules approach expiry.
Formulation claims. These cover stabilized, extended-release, and oral formulations, which are heavily patented, as formulation is where much peptide innovation and differentiation occurs.
Dosing-regimen and method-of-use claims. These cover titration schedules and specific therapeutic uses, and can block a product for a particular indication or regimen even when the molecule is otherwise available.
Delivery-device claims. These cover injection pens and other devices and are a large share of the thicket; peer-reviewed analysis found delivery devices accounted for the majority of listed GLP-1 patents and function as a distinct barrier to entry.¹,⁴
Process and manufacturing claims. These cover synthesis and purification routes, so a developer can be free to use a molecule yet blocked from a particular manufacturing method.
A single molecule illustrates the layering. A published patent landscape of one dual GLP-1/glucagon receptor agonist identified twelve patent families spanning composition-of-matter, process chemistry, formulation, dosing regimen, and method-of-use, a clean worked example of how all five claim types stack on one product.⁵
The thicket dynamic and the expiry landscape
The density of GLP-1 protection reflects a broader pharmaceutical pattern. Empirical analysis shows the number of patents filed per active ingredient rose from 1.86 in 2001 to nearly six by 2019, driven substantially by continuation applications, which account for roughly a third of small-molecule pharmaceutical patents.⁶ These secondary filings extend the effective protection period, and the economics of that extension, including how patent challenges and settlements shape effective market life, are well documented.⁷ Pharmaceutical thickets also differ structurally from thickets in complex-technology industries, which is why FTO methods developed for electronics do not transfer cleanly to peptides.⁸
The expiry landscape is the other half of the picture. As core molecules approach the end of composition-of-matter protection, the surrounding formulation, device, and process claims determine when and where competition can actually enter. Analysis of one leading GLP-1 molecule found that the timing of primary-patent expiry varies substantially by market, so freedom-to-operate for a follow-on product is jurisdiction-specific, and the practical entry date is governed by the secondary thicket rather than the headline molecule expiry.⁹ For a developer, this means FTO must be assessed claim-by-claim and market-by-market, not at the level of the molecule.
How AI-powered FTO helps
Navigating a thicket of this density by manual search is slow and prone to coverage gaps, which are the main source of FTO risk. AI-powered FTO addresses this with semantic search that retrieves relevant claims regardless of terminology, claim-level analysis that focuses on the independent claims defining infringement scope across all five claim types, and continuous monitoring that keeps a cleared position current as new formulation, device, and combination filings publish. Because peptide innovation appears in scientific literature before it is patented, reading both patents and literature gives earlier warning of where the thicket is extending.
Where Cypris fits
Cypris runs claim-level, semantic, AI-powered freedom-to-operate across a corpus of more than 500 million patents and scientific papers, organized through a proprietary R&D ontology. Semantic search across patents and scientific literature surfaces relevant claims regardless of terminology, across composition, formulation, dosing-regimen, delivery-device, and process claims, which is what a dense peptide thicket demands. The ontology clusters the thicket by concept and normalizes assignees, so a team sees the structure of protection around a molecule rather than a flat list. Cypris Q, the platform's agentic layer, lets teams run and chain FTO analysis conversationally, and Agentic Monitoring tracks a molecule and its surrounding thicket over time, flagging new formulation, device, and combination filings as they publish. Cypris provides enterprise API partnerships with OpenAI, Anthropic, and Google, and is built with enterprise-grade security. Cypris serves hundreds of enterprise customers across pharmaceuticals, chemicals, advanced materials, energy, and other regulated industries.
FAQ
Why is freedom-to-operate hard for GLP-1 and peptide therapeutics?
Freedom-to-operate is hard for GLP-1 and peptide therapeutics because protection is built as a dense, layered thicket extending well beyond the active ingredient. A peer-reviewed analysis found GLP-1 products carry a median of 19.5 listed patents each, most of them on delivery devices. Assessing FTO requires reading composition, formulation, dosing, device, and process claims across many patents and markets.
What claim types create FTO risk for GLP-1 products?
Five claim types create FTO risk for GLP-1 products: composition-of-matter claims on the peptide, formulation claims on stabilized and oral forms, dosing-regimen and method-of-use claims, delivery-device claims, and process or manufacturing claims. Each can independently block a product. Delivery-device claims are a particularly large share of the GLP-1 thicket.
How many patents protect a typical GLP-1 product?
A peer-reviewed analysis of GLP-1 receptor agonists approved between 2005 and 2021 found a median of 19.5 listed patents per product, with 54 percent on delivery devices rather than the active ingredient, and a median of 18.3 years of expected protection after approval. No generic manufacturer had successfully challenged a GLP-1 receptor agonist patent as of that analysis. These figures illustrate the density of the thicket.
What is a pharmaceutical patent thicket?
A pharmaceutical patent thicket is a dense set of overlapping patents around a single product that extends protection beyond the core molecule. Empirical analysis shows patents per active ingredient rose from 1.86 in 2001 to nearly six by 2019, driven substantially by continuation applications. Thickets shape when and where competition can enter.
How does the expiry of GLP-1 patents affect freedom-to-operate?
The expiry of GLP-1 patents affects freedom-to-operate market-by-market, because primary-patent expiry timing varies by jurisdiction and the practical entry date is governed by the surrounding formulation, device, and process claims rather than the molecule alone. FTO must therefore be assessed claim-by-claim and market-by-market. A molecule can be off-patent in one country and still protected in another.
Where is the white space in GLP-1 and peptide development?
Recent filing activity has shifted toward oral delivery, dual and triple receptor agonists, and combination therapies, which is where both new FTO risk and remaining white space now sit. Mapping this frontier requires reading patents and scientific literature together, since peptide innovation appears in research first. White space analysis identifies the areas that are still open.
How does AI-powered FTO help with peptide therapeutics?
AI-powered FTO helps with peptide therapeutics by using semantic search to retrieve relevant claims regardless of terminology, claim-level analysis to focus on the independent claims that define infringement across all claim types, and continuous monitoring to keep a cleared position current. This is what a dense, fast-moving thicket requires. Cypris runs this across more than 500 million patents and scientific papers.
Which teams need GLP-1 and peptide FTO analysis?
GLP-1 and peptide FTO analysis is needed by pharmaceutical and biotech R&D, IP, and business-development teams developing follow-on peptides, biosimilars, differentiated formulations, or combination products. It is also relevant to generics manufacturers assessing entry. Cypris serves hundreds of enterprise customers across pharmaceuticals and other regulated industries.
How current does GLP-1 FTO need to be?
GLP-1 FTO needs to be continuously current, because new formulation, device, dosing, and combination filings publish constantly and can change a cleared position. A one-time assessment reflects only the moment it was run. Cypris uses Agentic Monitoring to track a molecule and its surrounding thicket over time and flag new filings as they publish.
Endnotes
- Tu, S. S., Feldman, W. B., Alhiary, R., Gabriele, S., Kesselheim, A. S. & Beall, R. F. (2023). Patents and Regulatory Exclusivities on GLP-1 Receptor Agonists. JAMA. https://doi.org/10.1001/jama.2023.13872
- Industry analyst estimates (e.g., Research and Markets; BCC Research). GLP-1 market forecasts vary widely by scope and are presented here as order-of-magnitude estimates, not authoritative figures.
- Han, J., Zhou, Z., Jiang, N. & Lu, W. (2023). An updated patent review of GLP-1 receptor agonists (2020–present). Expert Opinion on Therapeutic Patents. https://doi.org/10.1080/13543776.2023.2274905
- Tu, S. S., Feldman, W. B. et al. (2024). Delivery Device Patents on GLP-1 Receptor Agonists. JAMA. https://doi.org/10.1001/jama.2024.0919
- Fasi, M. A. (2026). Patent landscape and therapeutic evolution of mazdutide. Expert Opinion on Therapeutic Patents. https://doi.org/10.1080/13543776.2026.2645812
- Tu, S. S. (2024). The Long CON: An Empirical Analysis of Pharmaceutical Patent Thickets. University of Pittsburgh Law Review. https://doi.org/10.5195/lawreview.2024.1049
- Hemphill, C. S. & Sampat, B. N. (2012). Evergreening, patent challenges, and effective market life in pharmaceuticals. Journal of Health Economics. https://doi.org/10.1016/j.jhealeco.2012.01.004
- Tu, S. S. & Carrier, M. A. (2023). Why Pharmaceutical Patent Thickets Are Unique. SSRN. https://doi.org/10.2139/ssrn.4571486
- Ramesh, S., Cross, S., Levi, J., Hill, A. & Venter, F. (2026). How Low Could Semaglutide Prices Fall? Implications for Global Access Ahead of Patent Expiry. Obesity. https://doi.org/10.1002/oby.70241
Perovskite-silicon tandem solar cells have become the clearest path to a real jump in solar-panel efficiency in decades, and their patent landscape is distinctive because the underlying physics gives every developer the same target while leaving wide latitude in how to reach it. A single-junction silicon cell is capped by a physical ceiling that combines the Shockley-Queisser detailed-balance limit with Auger recombination losses; a Fraunhofer ISE analysis that combines both effects puts the accurate theoretical efficiency limit for a silicon-based monolithic tandem at 43.2 percent¹. The path to that ceiling runs through several distinct patenting layers. Interface passivation is currently the dominant lever on record efficiency: mixed self-assembled monolayer (SAM) contacts first enabled a certified 28.3 percent tandem², further interface-passivation work pushed a certified cell to 31.25 percent³, and subsequent bilayer SAM strategies have continued to close the non-radiative recombination gap⁴. A separate, equally central problem is depositing perovskite uniformly onto the pyramid-textured surface of industrial silicon wafers — the texture that gives production-grade silicon its light-trapping advantage also makes uniform, defect-free perovskite deposition difficult, typically causing localized electrical leakage at the pyramid peaks. Proposed fixes include selective passivation of the pyramid tips specifically (32.9 percent reported)⁵, "iceberg-like" pyramid engineering compatible with industrial texturing (33 percent)⁶, and advanced light-management approaches for textured interfaces more broadly⁷. Because record efficiency and manufacturable durability are driven by different, not always overlapping, sets of techniques, freedom-to-operate and white space analysis must span composition, interface, and texture-compatible process together.
The field has moved from a laboratory curiosity to early commercial shipment within the past two years, even as the record-chasing and the product-shipping efforts remain distinct. The current widely cited two-terminal cell efficiency record is 34.85 percent, announced by LONGi and stated by the company to be NREL-certified — a figure that should be read as certified-per-developer disclosure at cell area, since the independent certification certificate itself was not directly available in this research pass, and it is not (as of this writing) also a peer-reviewed published result⁸. This record is categorically distinct from module-level performance: Oxford PV and Fraunhofer ISE reported a full-size commercial-format module at 25 percent efficiency, a genuinely different, lower, and non-comparable figure because module-area results inherently lag cell-area records⁹. Preserving this cell-versus-module distinction, and the related single-junction-perovskite-versus-tandem distinction, matters throughout any reading of the field's efficiency claims. Commercial shipment and pilot-line status is confirmed via primary company disclosure for Oxford PV⁹; comparable primary shipment-volume disclosures for other major developers were not located in this pass and should be treated as unconfirmed pending each company's own investor-relations or regulatory filing. Because applications publish about eighteen months after filing, the most recent passivation and encapsulation filings are under-represented, so the current frontier is more active than granted-patent counts suggest.
The strategic picture turns on which side of the record-versus-durability divide an owner is defending. Efficiency-record IP, concentrated in interface-passivation chemistry, is advancing quickly through a small number of well-resourced developers and research groups, and durability improvements are increasingly bundled with efficiency claims rather than reported separately in the most recent literature. The more open, commercially decisive ground remains the manufacturing and durability layer: deposition techniques compatible with textured industrial silicon at scale, and encapsulation and barrier-layer chemistry that closes the stability gap with silicon's multi-decade outdoor lifetime. Reading the landscape by layer, technique, and owner, and tracking both the patents and the underlying materials-science research, is what separates a workable manufacturing position from a blocked one.
Where the perovskite-silicon tandem white space is
Textured-silicon-compatible deposition. Depositing a uniform, leakage-free perovskite layer onto the pyramid-textured surface of industrial silicon wafers, rather than the flat substrates used for the highest record cells, is the central manufacturing barrier standing between lab records and mass production, with several distinct proposed solutions still competing⁵,⁶,⁷.
Encapsulation and durability chemistry bundled with efficiency. The most recent passivation literature increasingly targets stability and efficiency together rather than treating them as separate problems, which is itself a signal of where the field is converging.
Verified, primary-sourced commercial shipment data. Commercial shipment status is confirmed for Oxford PV via primary disclosure; comparable confirmation for other major developers remains outstanding, making rigorously verified shipment and production-volume claims a genuine differentiator.
Module-scale (not just cell-scale) efficiency. Because record efficiency is consistently reported at small cell area while commercial products are judged at full module scale, IP and technique that closes this cell-to-module gap is disproportionately valuable relative to further small-area record chasing.
Flexible and building-integrated form factors. Solution-processable, flexible tandem cells for curved surfaces, windows, and other building-integrated applications exploit perovskite's inherent advantages rather than competing directly with rigid silicon, and remain a less-crowded adjacent frontier.
How AI-powered landscape and white space analysis helps
Resolving a landscape that spans perovskite composition, interface chemistry, texture-compatible deposition, and encapsulation — where record-setting efficiency claims are announced by multiple developers within the same quarter, and where cell-area, module-area, certified, and company-announced figures are easily conflated — requires more than keyword search. AI-powered analysis addresses this with semantic search that clusters activity by layer and technique across varied terminology, attribution that normalizes solar-manufacturer, materials-supplier, and research-institution filers to canonical entities, and continuous monitoring that keeps pace with a field where the efficiency record itself changes multiple times a year. Because photovoltaics advances appear in materials-science literature before they are patented, reading both patents and literature gives the earliest signal of which technique is actually closing the gap between record cell and bankable product.
The competitive landscape by the numbers
The perovskite/tandem solar-cell patent family set totals roughly 12,575 documents, though this figure includes broader "tandem solar cell" and general photovoltaics art and therefore overstates perovskite-silicon-specific filings on its own (Cypris corpus, indicative; 2025–26 partial). Geography is led by China (approximately 1,994 families) and the United States (approximately 1,623), followed by Germany (approximately 846), Japan (approximately 773), and South Korea (approximately 758) (Cypris corpus, indicative; 2025–26 partial). Top assignees mix photovoltaics incumbents and materials firms — Trina Solar, Oxford Photovoltaics, Kaneka, LG, BASF, CEA, and JinkoSolar — alongside broader electronics players such as Canon and Toshiba, whose filings contribute some non-perovskite tandem/PV art to the set (Cypris corpus, indicative; 2025–26 partial). Filings show a recent perovskite-driven resurgence, rising from roughly 526 families in 2021 to about 1,191 in 2025 (Cypris corpus, indicative; 2025–26 partial).
Where Cypris fits
Cypris runs patent landscape and white space analysis for fast-moving materials fields such as perovskite-silicon tandem photovoltaics across a corpus of more than 500 million patents and scientific papers, organized through a proprietary R&D ontology. The ontology clusters activity by layer, perovskite composition, interface passivation, tandem architecture, and encapsulation, and normalizes solar-manufacturer, materials-supplier, and research-institution filers to canonical entities, so a team can resolve which layers and techniques are crowded and which remain open as white space. Semantic search across patents and scientific literature connects filings to the underlying materials-science research, which is where tandem-cell advances appear first, often well ahead of the patent record. Cypris Q, the platform's agentic layer, lets teams run landscape and white space analysis conversationally and chain the clustering, attribution, and gap analysis, and Agentic Monitoring tracks a defined layer over time and flags new patents and papers as they publish. Cypris provides enterprise API partnerships with OpenAI, Anthropic, and Google, and is built with enterprise-grade security. Cypris serves hundreds of enterprise customers across pharmaceuticals, chemicals, advanced materials, energy, and other regulated industries.
FAQ
What is a perovskite-silicon tandem solar cell? A perovskite-silicon tandem solar cell stacks a perovskite top cell on top of a crystalline-silicon bottom cell so the combined device captures more of the solar spectrum than either material could alone, allowing it to exceed the theoretical ceiling that limits any single-junction silicon cell. That combined ceiling, accounting for both Shockley-Queisser and Auger effects, is calculated at 43.2 percent¹. The current company-reported, NREL-certified cell-area record stands at 34.85 percent⁸.
Why can't a single-junction silicon cell just be made more efficient instead? A single-junction silicon cell cannot exceed its combined Shockley-Queisser/Auger efficiency ceiling because that limit is set by the fundamental physics of extracting energy from a broad-spectrum light source using a single semiconductor bandgap, not by manufacturing quality¹. Continuing to refine single-junction silicon can approach that limit but never exceed it. Stacking a second, complementary-bandgap material is the only way to break through it.
What layers does the tandem patent landscape cover? The landscape covers perovskite composition and bandgap engineering, interface passivation chemistry, tandem cell architecture compatible with industrial silicon texturing, and encapsulation and stability engineering. Interface passivation is currently the dominant lever on record efficiency²,³,⁴, while texture-compatible deposition remains the central manufacturing barrier⁵,⁶,⁷. A bankable product depends on progress across all of these layers together.
Are perovskite-silicon tandem panels available to buy in 2026? Only in limited volume, and only confirmed for certain developers. Oxford PV has a confirmed primary disclosure of a full-size commercial-format module reaching 25 percent efficiency in partnership with Fraunhofer ISE⁹, but comparable shipment-volume confirmation for other major manufacturers was not available in current primary disclosures. The efficiency record (34.85 percent, cell-area) and the shipping product (25 percent, module-area) are currently very different numbers describing different things.
Where is the white space in perovskite-silicon tandem solar cells? The white space includes textured-silicon-compatible deposition, durability chemistry bundled with efficiency gains, verified commercial shipment data, closing the cell-to-module efficiency gap, and flexible or building-integrated form factors. Record-efficiency IP is advancing quickly through interface-passivation chemistry specifically. The manufacturing, durability, and module-scale layers are the more open and commercially decisive ground.
Why is depositing perovskite onto textured silicon so hard? Depositing perovskite onto textured silicon is hard because industrial silicon wafers use a pyramid-textured surface to trap light and boost efficiency, but that same texture makes it difficult to deposit a uniform, defect-free perovskite layer, often causing localized electrical leakage at the pyramid peaks. The highest record cells are typically demonstrated on flatter or smaller-area substrates that partially avoid this problem. Multiple distinct fixes are being pursued in parallel, including selective peak passivation and engineered pyramid geometry⁵,⁶.
Why does perovskite-silicon tandem analysis need scientific literature? Perovskite-silicon tandem analysis needs scientific literature because composition, passivation, and encapsulation advances appear in materials-science research before they are patented, and because distinguishing certified from company-announced figures, and cell-area from module-area results, requires reading the primary literature rather than press coverage. Analyzing patents alone gives a lagging view. Cypris analyzes both across more than 500 million patents and scientific papers.
Which teams use perovskite-silicon tandem patent landscape analysis? Perovskite-silicon tandem patent landscape analysis is used by R&D, IP, and strategy teams at solar manufacturers and materials suppliers, as well as investors assessing the photovoltaics sector. Because record efficiency and commercial durability are driven by different techniques at different maturity levels, and because efficiency claims require careful certified-versus-announced and cell-versus-module verification, structured analysis is essential. Cypris serves hundreds of enterprise customers across advanced materials, energy, and other research-intensive industries.
Endnotes
- Schubert MC, Glunz SW, Fell A, Bivour M, Messmer C. Elucidating the efficiency limit of silicon-based monolithic tandem cells through the combination of Auger and Shockley-Queisser limits. EES Solar. DOI: 10.1039/d5el00085h.
- Kishimoto K, Uzu H, Yamamoto K, Yoshida W, Okamoto S. 28.3% efficient perovskite-silicon tandem solar cells with mixed self-assembled monolayers. Applied Physics Express. DOI: 10.35848/1882-0786/ac727b.
- Artuk K, Sahli F, Jeangros Q, Boccard M, Tabean S. Interface passivation for 31.25%-efficient perovskite/silicon tandem solar cells. Science. DOI: 10.1126/science.adg0091.
- Jia Y, Xu X, Li P, Li Z, Xiao C. Perovskite/silicon tandem solar cells with bilayer interface passivation. Nature. DOI: 10.1038/s41586-024-07997-7.
- Ye JP, Yang X, Ying Z, Du H, Yang W. Selective passivation of pyramid peaks for 32.9%-efficient perovskite/silicon tandem solar cells. Matter. DOI: 10.1016/j.matt.2026.102824.
- Wei J, Li R, Yu X, Hang P, Wu T. Iceberg-like pyramids in industrially textured silicon enabled 33% efficient perovskite-silicon tandem solar cells. Nature Communications. DOI: 10.1038/s41467-025-62389-3.
- Stannowski B, Korte L, Jošt M, Al-Ashouri A, Lipovšek B. Textured interfaces in monolithic perovskite/silicon tandem solar cells: advanced light management for improved efficiency and energy yield. Energy & Environmental Science. DOI: 10.1039/c8ee02469c.
- LONGi Green Energy. 34.85%! LONGi Breaks World Record for Crystalline Silicon-Perovskite Tandem Solar Cell Efficiency Again. Company press release, longi.com.
- Oxford PV and Fraunhofer ISE. Oxford PV and Fraunhofer ISE Develop Full-sized Tandem PV Module with Record Efficiency of 25 Percent. Fraunhofer ISE press release, ise.fraunhofer.de.
- Cypris platform corpus analysis, perovskite/tandem solar-cell patent families. Indicative figures; 2025–2026 partial.
Commercial fusion energy has moved from a distant public-research goal to a well-funded private race, and its patent landscape is being staked out as companies compress decades of physics into engineering programs. Fusion fuses light nuclei to release energy, and its progress is measured by the fusion gain, or Q, and the triple product of density, temperature, and confinement time, the parameters that determine whether a device produces more energy than it consumes.³ It is pursued through several competing confinement approaches, each a distinct region of patenting: magnetic confinement, including tokamaks, spherical tokamaks such as Globus-M2, stellarators, mirrors, and field-reversed configurations; inertial confinement using lasers; and magneto-inertial hybrids, running on fuels such as deuterium-tritium, deuterium-deuterium, and proton-boron.⁵ The intellectual property divides across the enabling technologies these approaches share: the magnets that confine the plasma, especially high-temperature superconducting magnets; the systems that heat and control the plasma; the tritium breeding blankets that must produce fuel and capture energy; the first-wall and divertor materials that survive intense neutron flux; and, for inertial approaches, the targets and drivers, whose implosion physics is an active research area.¹,⁶ Because a viable plant depends on several of these layers, freedom-to-operate and white space analysis must span the confinement approaches and the enabling layers together.
The landscape is being reshaped by a technology shift and a funding boom. High-temperature superconducting magnets, which reach much stronger fields than conventional superconductors, allow far more compact and potentially cheaper machines: the SPARC device, for example, is designed around a high-field, compact tokamak concept, and the physics basis for such burning-plasma machines is now well documented.² The 2025 edition of the IAEA's World Fusion Outlook gave these magnets a special focus, reflecting their role across tokamaks, stellarators, and mirror concepts.⁹ Public milestones anchor the field: in December 2022 the US National Ignition Facility achieved fusion ignition, producing about 3.15 megajoules of fusion energy from about 2.05 megajoules of laser energy delivered to the target, a scientific, target-level energy gain rather than a net-grid gain, and later experiments repeated ignition.⁷ On the magnetic side, ITER's 2024 re-baseline set the start of research operations in 2034 and the start of deuterium-tritium operations in 2039, a four-year delay from the earlier reference, and changed the first-wall material from beryllium to tungsten.⁸ Public programs are also advancing the physics, as with China's HL-3 tokamak.⁴ The intellectual-property picture is therefore a mix, because much of the underlying plasma physics is in the public domain from decades of open research, while the proprietary value concentrates in the specific engineering that turns physics into a machine. That split is visible in the record: across the Cypris corpus of more than 500 million patents and scientific papers, the fusion set holds on the order of 11,694 families and grew from about 376 in 2020 to roughly 711 in 2024, with the most active assignees being public institutes and diversified industrials, led by the Hefei Institutes of Physical Science of the Chinese Academy of Sciences alongside Toshiba, Hitachi, and the Japan Atomic Energy Agency, and China ahead of the United States and the United Kingdom on geography; 2025 and 2026 counts are partial because of the publication lag.
The strategic question is which enabling layer to own, and the white space sits where engineering, not physics, is the barrier. High-temperature superconducting magnet design and the manufacturing of the superconducting tape and cable are a high-value layer where a compact-machine advantage is won.² Tritium breeding, producing more tritium than the plant consumes, has not been demonstrated at commercial scale and is a critical, comparatively open area, as are the first-wall and divertor materials that must withstand neutron damage over a plant's life. Plasma heating and control, increasingly aided by machine learning, and, for inertial approaches, target fabrication and drivers, are further contested layers.⁶ Private-venture pilot-plant dates and net-gain targets should be read as company projections rather than demonstrated results. Reading the landscape by approach, enabling layer, and owner, and tracking both the patents and the underlying fusion-science research, is what separates a crowded region from an open one.
Where the fusion white space is
High-temperature superconducting magnets. Magnet design and the manufacturing of superconducting tape and cable for compact, high-field machines are a high-value, capital-intensive layer.²
Tritium breeding blankets. Breeding more tritium than the plant consumes, and capturing the fusion energy, is unproven at commercial scale and a critical, comparatively open area.
First-wall and divertor materials. Materials such as tungsten that survive intense neutron flux over a plant's life, and the strategies to replace them, are a distinct, high-stakes engineering layer.⁸
Plasma heating and control. Systems that heat, shape, and stabilize the plasma, increasingly using machine learning, are an active and contested layer.
Inertial targets and drivers. For inertial-confinement approaches, target fabrication and driver technologies are a separate region of patenting.¹,⁶
How AI-powered landscape and white space analysis helps
Resolving a landscape that spans several confinement approaches and enabling layers, built on public physics but proprietary engineering, requires more than keyword search. AI-powered analysis addresses this with semantic search that clusters activity by approach and enabling layer across varied terminology, attribution that normalizes private, public, and academic filers to canonical entities, and continuous monitoring that keeps pace with a fast-funding field. Because fusion advances appear in scientific literature before they are patented, and because so much of the science is public while the engineering is proprietary, reading both patents and literature is essential to separate open physics from claimable engineering.
Where Cypris fits
Cypris runs patent landscape and white space analysis for engineering-intensive deep-tech fields such as commercial fusion energy across a corpus of more than 500 million patents and scientific papers, organized through a proprietary R&D ontology. The ontology clusters activity by confinement approach, tokamak, stellarator, inertial, and others, and by enabling layer, magnets, heating and control, tritium breeding, materials, and targets, and normalizes private, public, and academic filers to canonical entities, so a team can resolve which approaches and layers are crowded and which remain open as white space. Semantic search across patents and scientific literature connects filings to the underlying fusion-science research, which is where advances appear first and where public physics must be separated from proprietary engineering. Cypris Q, the platform's agentic layer, lets teams run landscape and white space analysis conversationally and chain the clustering, attribution, and gap analysis, and Agentic Monitoring tracks a defined layer over time and flags new patents and papers as they publish. Cypris provides enterprise API partnerships with OpenAI, Anthropic, and Google, and is built with enterprise-grade security. Cypris serves hundreds of enterprise customers across pharmaceuticals, chemicals, advanced materials, energy, and other regulated industries.
FAQ
What is the commercial fusion energy patent landscape? The commercial fusion energy patent landscape is the set of patents covering the technologies needed to build a fusion power plant. It spans confinement approaches, tokamaks, stellarators, inertial, and others, and enabling layers such as magnets, plasma heating and control, tritium breeding, first-wall materials, and inertial targets. Each is a distinct region of patenting.
Why are high-temperature superconducting magnets so important? High-temperature superconducting magnets are important because they reach much stronger magnetic fields than conventional superconductors, which allows far more compact and potentially cheaper fusion machines. They have become a central engineering and patenting focus across several confinement approaches, and the 2025 IAEA World Fusion Outlook gave them a special focus. Magnet design and superconducting-tape manufacturing are high-value layers.
Why is tritium breeding a key white space? Tritium breeding is a key white space because a deuterium-tritium plant must produce more tritium than it consumes to be self-sufficient, and this has not been demonstrated at commercial scale. The breeding blanket must also capture the fusion energy and survive neutron flux. That combination makes it a critical, comparatively open engineering layer.
What did the NIF ignition result actually show? The National Ignition Facility achieved fusion ignition in December 2022, producing about 3.15 megajoules of fusion energy from about 2.05 megajoules of laser energy delivered to the target. This is a scientific, target-level energy gain, not a net-grid gain, because the laser system draws far more energy from the grid than reaches the target. Later experiments repeated ignition.
How does public physics affect fusion IP? Public physics affects fusion IP because decades of open, publicly funded research placed much of the underlying plasma physics in the public domain, so the proprietary, patentable value concentrates in the specific engineering, magnets, blankets, materials, targets, and control systems, that turns physics into a working machine. Distinguishing public science from claimable engineering is central to fusion freedom-to-operate.
Where is the white space in fusion energy? The white space includes high-temperature superconducting magnets and their manufacturing, tritium breeding blankets, first-wall and divertor materials, plasma heating and control including machine-learning approaches, and inertial targets and drivers. The physics is largely public. The most open, high-value opportunities are in the engineering layers that remain unproven at commercial scale.
Why does fusion analysis need scientific literature? Fusion analysis needs scientific literature because so much of the field's knowledge is in public research, and new engineering advances appear in the literature before they are patented, so reading both is essential to separate open physics from claimable engineering. Analyzing patents alone gives a partial view. Cypris analyzes both across more than 500 million patents and scientific papers.
What software helps analyze the fusion energy patent landscape? Software for the fusion landscape should cluster activity by confinement approach and enabling layer, resolve private, public, and academic filers to canonical owners, search patents and scientific literature semantically, and monitor a fast-funding field continuously. Cypris does this across more than 500 million patents and scientific papers using a proprietary R&D ontology, semantic search, Cypris Q, and Agentic Monitoring.
Endnotes
- Chapman, T. D., Ralph, J. E., Woodworth, B., et al. (2024). Present understanding of ignition and gain using indirect-drive inertial confinement fusion on the U.S. National Ignition Facility. Plasma Physics and Controlled Fusion, 67(1). https://doi.org/10.1088/1361-6587/ad994f
- Creely, A. J., Rice, J. E., Sorbom, B. N., Hartwig, Z. S., et al. (2022). Overview of the SPARC physics basis toward burning-plasma regimes in high-field, compact tokamaks. Nuclear Fusion, 62(4). https://doi.org/10.1088/1741-4326/ac1654
- Costley, A. E. (2016). On the fusion triple product and fusion power gain of tokamak pilot plants and reactors. Nuclear Fusion, 56(6). https://doi.org/10.1088/0029-5515/56/6/066003
- Chen, W., & Zhong, W. (2025). Breakthrough in China's fusion energy: HL-3 tokamak achieves high ion temperature and fusion triple product. The Innovation, 6. https://doi.org/10.1016/j.xinn.2025.101167
- Sakharov, N. V., et al. (2021). Tenfold increase in the fusion triple product in the spherical tokamak Globus-M2. Nuclear Fusion, 61(6). https://doi.org/10.1088/1741-4326/abe08c
- Zhou, Y., Sadler, J. D., & Hurricane, O. A. (2024). Instabilities and mixing in inertial confinement fusion. Annual Review of Fluid Mechanics, 57. https://doi.org/10.1146/annurev-fluid-022824-110008
- U.S. Department of Energy (2022, December 13). DOE National Laboratory makes history by achieving fusion ignition. https://www.energy.gov/articles/doe-national-laboratory-makes-history-achieving-fusion-ignition
- ITER Organization (2024). New baseline to prioritize a robust start to exploitation. https://www.iter.org/node/20687/new-baseline-prioritize-robust-start-exploitation
- International Atomic Energy Agency (2025). Fusion energy in 2025: six global trends to watch (World Fusion Outlook 2025). https://www.iaea.org/newscenter/news/fusion-energy-in-2025-six-global-trends-to-watch
Silicon photonics has moved to the center of AI infrastructure, and its patent landscape is being staked out as data centers hit a wall that electrical interconnects cannot cross. As AI clusters scale to enormous numbers of accelerators, the energy and bandwidth cost of moving data over copper between chips, boards, and racks has become a dominant constraint, and peer-reviewed work frames high-bandwidth-density, energy-efficient optical interconnects as the leading answer.¹,² The technology arrives in several forms, each a distinct region of patenting: co-packaged optics, which place the optical engine in the same package as the switch or accelerator; optical input-output chiplets that bring light directly to the compute die; and silicon-photonic network switches. The intellectual property divides across the photonic devices themselves, such as modulators and detectors; the photonic-electronic integration and advanced packaging that combine light and electronics; the laser and light-source technologies that feed them; and the system-level architecture that ties them into an AI fabric. Because a working optical interconnect depends on several of these layers, freedom-to-operate and white space analysis must span them together.
The landscape is moving from roadmap to product very quickly, and it is quantitatively demanding. Peer-reviewed co-packaged transceivers now report energy efficiencies on the order of 3 picojoules per bit at hundreds of gigabits per second per channel, and advanced through-silicon and through-glass interposer packaging has demonstrated bandwidths beyond 67 and 110 gigahertz, illustrating both the device-level and packaging-level progress.³,⁶,⁷ Standardization is advancing alongside the hardware: the chiplet-interconnect standard released a new version in August 2025 adding higher data rates and extended reach, shaping how photonic engines connect to compute.⁸,⁹ Major networking and accelerator vendors have introduced co-packaged optical switches and optical I/O, but the competitive structure is layered rather than winner-take-all. Across the Cypris corpus of more than 500 million patents and scientific papers, the silicon-photonics, co-packaged-optics, and optical-interconnect space holds on the order of 102,700 de-duplicated families and has grown steadily and with acceleration, and the most active assignees are systems and networking vendors and foundries and research institutes, led by firms such as Intel, Huawei, IBM, NTT, TSMC, Cisco, and Marvell together with foundries and research organizations such as GlobalFoundries and imec, rather than pure-play startups, which do not appear in the top tier; the United States leads on geography, followed by China, Japan, and Taiwan. Because applications publish about eighteen months after filing, the most recent modulator, integration, and packaging filings are under-represented (2025 counts are partial), so the current frontier is more active than granted-patent counts suggest.
The strategic question is which layer to own, and the white space sits where physics and manufacturing are hardest. High-speed, low-power modulators are a foundational device layer where efficiency gains translate directly into system power savings, and microring-based modulator designs are a central approach.⁴,⁵ Photonic-electronic integration and packaging, bringing light reliably to the compute die at yield and scale, is the central manufacturing challenge and where much of the defensible, hard-to-design-around IP is concentrating.⁶,⁷ In the Cypris corpus, the modulator and light-source layers are the most heavily patented, followed by integration and packaging and then optical I/O, so laser and light-source integration is a distinct and contested layer, and system-level architecture, how optical links reshape the AI fabric, is where differentiation is won. Reading the landscape by layer and by owner, and tracking both the patents and the underlying photonics research, is what separates a crowded region from an open one.
Where the silicon photonics white space is
High-speed, low-power modulators. Modulators that raise data rates while cutting energy per bit are a foundational device layer where gains flow straight to system power.⁴,⁵
Photonic-electronic integration and packaging. Bringing light to the compute die at yield and scale is the central manufacturing challenge and where much hard-to-design-around IP concentrates.⁶,⁷
Laser and light-source integration. Efficient, reliable on- and off-package light sources are a distinct and contested layer, and among the most heavily patented in the corpus.
Optical I/O chiplets and interfaces. Chiplet-based optical I/O and the standardized interfaces that connect it to compute are an active, fast-moving layer.⁸,⁹
System-level optical architecture. Designs that reshape the AI fabric around optical links, including optical switching, are where system differentiation is won.
How AI-powered landscape and white space analysis helps
Resolving a landscape that spans photonic devices, integration and packaging, light sources, and system architecture, in a field moving from roadmap to product month to month, requires more than keyword search. AI-powered analysis addresses this with semantic search that clusters activity by layer across varied terminology, attribution that normalizes vendor, foundry, and startup filers to canonical entities, and continuous monitoring that keeps pace with a fast-moving field. Because silicon-photonics advances appear in scientific and conference literature before they are patented, reading both patents and literature gives the earliest signal of where the frontier and the white space are moving.
Where Cypris fits
Cypris runs patent landscape and white space analysis for fast-moving deep-tech fields such as silicon photonics for AI across a corpus of more than 500 million patents and scientific papers, organized through a proprietary R&D ontology. The ontology clusters activity by layer, photonic device, integration and packaging, light source, optical I/O, and system architecture, and normalizes vendor, foundry, and startup filers to canonical entities, so a team can resolve which layers are crowded and which remain open as white space. Semantic search across patents and scientific literature connects filings to the underlying photonics research, which is where silicon-photonics advances appear first, often well ahead of the patent record. Cypris Q, the platform's agentic layer, lets teams run landscape and white space analysis conversationally and chain the clustering, attribution, and gap analysis, and Agentic Monitoring tracks a defined layer over time and flags new patents and papers as they publish. Cypris provides enterprise API partnerships with OpenAI, Anthropic, and Google, and is built with enterprise-grade security. Cypris serves hundreds of enterprise customers across pharmaceuticals, chemicals, advanced materials, energy, and other regulated industries.
FAQ
Why is silicon photonics central to AI infrastructure? Silicon photonics is central to AI infrastructure because AI clusters have grown so large that moving data over copper between chips, boards, and racks consumes too much power and limits bandwidth. Optical interconnects move data as light, cutting interconnect power and raising bandwidth. That is why co-packaged optics and optical I/O have moved from roadmap to product.
What layers does the silicon photonics landscape cover? The landscape covers photonic devices such as modulators and detectors, photonic-electronic integration and advanced packaging, laser and light-source technologies, optical I/O chiplets and interfaces, and system-level optical architecture. Each is a distinct region of patenting with different owners. Freedom-to-operate and white space analysis must span them together.
Who holds the IP in silicon photonics for AI? In the Cypris corpus, the most active assignees are systems and networking vendors, foundries, and research institutes, rather than pure-play startups, which do not appear in the top tier. Ownership is distributed across the stack, from modulators and integration to light sources and architecture. That layered structure makes landscape analysis valuable.
Where is the white space in silicon photonics? The white space includes high-speed, low-power modulators, photonic-electronic integration and packaging, laser and light-source integration, optical I/O chiplets and interfaces, and system-level optical architecture. Integration and packaging is the central manufacturing challenge and where much hard-to-design-around IP concentrates. The modulator and light-source layers are the most heavily patented in the corpus.
Why is integration and packaging so important? Integration and packaging is important because the hardest part of optical interconnects is bringing light reliably to the compute die at high yield and large scale. Solving this at manufacturable cost is what turns a device advantage into a system advantage. Much of the defensible, hard-to-design-around IP is concentrating there.
Why does silicon photonics analysis need scientific literature? Silicon photonics analysis needs scientific literature because device, integration, and light-source advances appear in research and conference proceedings before they are patented, so the literature gives the earliest signal in a fast-moving field. Analyzing patents alone gives a lagging view. Cypris analyzes both across more than 500 million patents and scientific papers.
What software helps analyze the silicon photonics patent landscape? Software for the silicon photonics landscape should cluster activity by device, integration, light-source, and architecture layer, resolve vendor, foundry, and startup filers to canonical owners, search patents and scientific literature semantically, and monitor a fast-moving field continuously. Cypris does this across more than 500 million patents and scientific papers using a proprietary R&D ontology, semantic search, Cypris Q, and Agentic Monitoring.
Which teams use silicon photonics patent landscape analysis? Silicon photonics patent landscape analysis is used by R&D, IP, and strategy teams at semiconductor, networking, photonics, and data-center companies, as well as investors assessing the sector. Because ownership is distributed across the stack and the field is moving fast, structured analysis is essential. Cypris serves hundreds of enterprise customers across research-intensive and regulated industries.
Endnotes
- Novick, A., James, A., Wu, L. Y., Hattink, M., et al. (2023). High-bandwidth-density silicon photonic resonators for energy-efficient optical interconnects. Applied Physics Reviews, 10(3). https://doi.org/10.1063/5.0160441
- Priyadarshi, S. (2025). Unlocking the potential of co-packaged optics in AI and HPC: opportunities and challenges. IEEE Communications Magazine. https://doi.org/10.1109/mcom.001.2500504
- Li, X., Li, Y., Zhao, Y., Zhong, K., et al. (2025). Monolithically integrated 4×128 Gb/s, 3.07 pJ/bit silicon photonic transceiver for co-packaged optics. Optics Express, 33. https://doi.org/10.1364/oe.577010
- Wu, Y., He, J., Cao, Y., & Liu, L. (2022). The high-efficiency co-design and measurement verification of high-bandwidth silicon photonic microring modulator. IET Optoelectronics, 16(6). https://doi.org/10.1049/ote2.12070
- Titriku, A., Palermo, S., Chen, C.-H., Fiorentino, M., et al. (2015). Silicon photonic microring resonator-based transceivers for compact WDM optical interconnects. IEEE Compound Semiconductor Integrated Circuit Symposium (CSICS). https://doi.org/10.1109/csics.2015.7314523
- Molnar, A., Ou, Y., Khilwani, D., et al. (2025). Scaling co-packaged optical interconnects using hybrid 2.5D/3D integration. IEEE International Symposium on Circuits and Systems (ISCAS). https://doi.org/10.1109/iscas56072.2025.11043946
- Liu, S., Zhang, Y., Ge, C., Du, Y., et al. (2026). High-density co-packaged optics based on TSV and TGV interposers. Advanced Photonics Nexus, 5(3). https://doi.org/10.1117/1.apn.5.3.036019
- UCIe Consortium. Universal Chiplet Interconnect Express (UCIe) specifications. https://www.uciexpress.org/specifications
- Das Sharma, D., et al. (2024). High-performance, power-efficient three-dimensional system-in-package designs with universal chiplet interconnect express. Nature Electronics, 7. https://doi.org/10.1038/s41928-024-01126-y
CAR-T cell therapy has one of the most academically rooted and legally tested patent landscapes in biotechnology. A chimeric antigen receptor T-cell is engineered by giving a patient's T-cells a synthetic receptor that directs them against a cancer target, and the intellectual property spans several distinct layers: the CAR construct itself, with its antigen-binding domain, hinge, transmembrane region, costimulatory domain, and signaling domain; the viral vectors used to introduce it; the manufacturing and cell-processing methods; and the methods of use for specific indications. Because these layers are patented separately and often by different owners, freedom-to-operate for a CAR-T product is a multi-layer, multi-owner analysis rather than a single clearance.
The foundational patents emerged from academic laboratories and were then in-licensed or acquired by commercial developers, which shaped the ownership structure. Peer-reviewed analyses of CAR-T patenting activity trace the field's key early filings to academic groups, with foundational work associated with Carl June at the University of Pennsylvania and Michel Sadelain at Memorial Sloan Kettering Cancer Center, before commercialization by large pharmaceutical companies.¹,² This academic origin is visible in the ownership record: across the Cypris corpus of more than 500 million patents and scientific papers, the most active assignees in the CAR-T set are led by the University of Pennsylvania, followed by the US Department of Health and Human Services and the National Institutes of Health, the University of California San Diego, the University of Texas System, and Memorial Sloan Kettering, interleaved with commercial developers such as Novartis, Juno Therapeutics, and Kite Pharma. Peer-reviewed patent-landscape analyses describe a field of fierce competition and intensive academic-industry collaboration,¹ with one review mapping more than 1,600 patent families across the field's technological routes,³ and product-patent-linkage studies have detailed how the portfolios behind approved CAR-T products are assembled from the construct, vector, manufacturing, and method-of-use layers.⁴ Analyses of academic CAR-T patenting also document the pitfalls that arise when university filings are drafted for disclosure rather than durable claim scope.⁵ A recurring finding is that many foundational filings date to the late 1990s and early 2000s, so their earliest members are now reaching the end of their patent terms, which shifts value toward improvement patents on next-generation constructs, allogeneic and off-the-shelf approaches, and manufacturing.¹,³ Across the Cypris corpus, CAR-T patent families grew from about 2,882 in 2018 to about 9,118 in 2024, with 2025 counts partial because of the roughly eighteen-month publication lag.
Litigation defined the landscape's risk profile. In the dispute between Juno Therapeutics, which exclusively licensed a foundational receptor patent from Memorial Sloan Kettering, and Kite Pharma over its approved therapy, a jury initially found for Juno, but on August 26, 2021 the US Court of Appeals for the Federal Circuit reversed and held the foundational patent's asserted claims invalid for lack of adequate written description, reasoning that disclosing a small number of specific binding domains did not show possession of the far broader claimed genus.⁶ A peer-reviewed analysis in Biotechnology Law Report situated the decision as a strike against broadly drafted, pioneering biotechnology claims.⁷ The decision reshaped the field, because it raised questions about the validity of broadly drafted foundational biotech patents generally, and it signaled that in cell therapy the durable value may lie in specific, well-supported improvement claims rather than pioneering-but-broad foundational ones. Because applications publish about eighteen months after filing, the most recent activity in next-generation and allogeneic approaches is under-represented, so the current frontier is more active than granted-patent counts suggest.
What creates FTO risk in CAR-T products
CAR construct claims. These cover the receptor's components, including antigen-binding domain, costimulatory domain, and signaling domain, the core of many disputes.
Viral vector claims. These cover the vectors used to introduce the receptor, a distinct and separately owned layer.
Manufacturing and cell-processing claims. These cover how the therapy is produced, which is increasingly where competitive differentiation and IP concentrate.
Method-of-use claims. These cover use for specific indications and patient populations, so a construct can be free for one use and blocked for another.
Next-generation and allogeneic claims. These cover off-the-shelf, gene-edited, and next-generation approaches, a fast-growing layer where new FTO risk and white space are emerging.
How AI-powered landscape and FTO analysis helps
A multi-layer, academically rooted, litigated landscape is beyond manual clearance. AI-powered analysis addresses this with semantic search that retrieves relevant construct, vector, manufacturing, and use claims regardless of terminology, attribution that resolves academic and commercial owners to canonical entities and captures the license and acquisition chains, and continuous monitoring that tracks next-generation filings and litigation developments. Because cell-therapy advances appear in scientific literature before they are patented, reading both patents and literature gives earlier warning.
Where Cypris fits
Cypris runs patent landscape and freedom-to-operate analysis for multi-layer, academically rooted fields such as CAR-T across a corpus of more than 500 million patents and scientific papers, organized through a proprietary R&D ontology. The ontology clusters the landscape by layer, construct, vector, manufacturing, and use, and normalizes academic and commercial owners to canonical entities, so a team can trace how rights and licenses are distributed rather than read a flat list. Semantic search across patents and scientific literature surfaces relevant claims regardless of terminology and connects filings to the underlying research, which is where next-generation and allogeneic approaches emerge first. Cypris Q, the platform's agentic layer, lets teams run landscape and FTO analysis conversationally and chain the attribution, clustering, and claim-level analysis, and Agentic Monitoring tracks the landscape over time and flags new filings and developments as they publish. Cypris provides enterprise API partnerships with OpenAI, Anthropic, and Google, and is built with enterprise-grade security. Cypris serves hundreds of enterprise customers across pharmaceuticals, chemicals, advanced materials, energy, and other regulated industries.
FAQ
Why is the CAR-T patent landscape distinctive? The CAR-T patent landscape is distinctive because it is deeply rooted in academic research and has been heavily litigated. Foundational patents came from university labs and were licensed or acquired by commercial developers, and the IP spans the receptor construct, viral vectors, manufacturing, and methods of use. Freedom-to-operate is therefore a multi-layer, multi-owner analysis.
What claim types create FTO risk in CAR-T? Five claim types create FTO risk in CAR-T: CAR construct claims, viral vector claims, manufacturing and cell-processing claims, method-of-use claims, and next-generation or allogeneic claims. Each is independently patentable and can be held by a different owner. Construct and manufacturing layers are especially contested.
What was the Juno v. Kite decision? In Juno v. Kite, Juno Therapeutics asserted a foundational CAR receptor patent it had licensed from Memorial Sloan Kettering against Kite Pharma's approved therapy. A jury initially found for Juno, but the US Court of Appeals for the Federal Circuit in 2021 reversed and struck down the foundational patent for lack of adequate written description. The decision reshaped the field and raised questions about broadly drafted foundational biotech patents.
Why are CAR-T foundational patents reaching the end of their terms important? Many CAR-T foundational filings date to the late 1990s and early 2000s, so their earliest members are now reaching the end of their patent terms, which shifts value away from the original broad claims toward improvement patents. These cover next-generation constructs, allogeneic and off-the-shelf approaches, and manufacturing. FTO analysis must therefore focus increasingly on the improvement layer.
Where did CAR-T foundational patents come from? CAR-T foundational patents came largely from academic laboratories, with key work associated with Carl June at the University of Pennsylvania and Michel Sadelain at Memorial Sloan Kettering Cancer Center. These filings were in-licensed or acquired by commercial developers who brought products to market. This academic origin shaped the landscape's ownership and licensing structure, which is visible in the assignee record.
Why does CAR-T analysis need scientific literature? CAR-T analysis needs scientific literature because construct, manufacturing, and next-generation advances appear in research before they are patented, so the literature gives the earliest signal of where the field is heading. Analyzing patents alone gives a lagging view. Cypris analyzes both across more than 500 million patents and scientific papers.
Which teams need CAR-T patent landscape and FTO analysis? CAR-T patent landscape and FTO analysis is needed by R&D, IP, and business-development teams at cell-therapy and pharmaceutical companies, academic technology-transfer offices, and investors assessing cell-therapy assets. The multi-layer, litigated landscape makes structured analysis essential. Cypris serves hundreds of enterprise customers across pharmaceuticals and other research-intensive industries.
How current does a CAR-T landscape need to be? A CAR-T landscape needs to be continuously current, because foundational patents are reaching the end of their terms, next-generation and allogeneic filings publish constantly, and publication lag hides the most recent activity. A one-time landscape ages quickly. Cypris uses Agentic Monitoring to track the landscape and flag new filings and developments as they publish.
Endnotes
- Lyu, L., Chen, X., Hu, Y., & Feng, Y. (2020). The global chimeric antigen receptor T (CAR-T) cell therapy patent landscape. Nature Biotechnology, 38(12). https://doi.org/10.1038/s41587-020-00749-8
- Clarke, N. S., & Jürgens, B. (2019). Evolution of CAR T-cell immunotherapy in terms of patenting activity. Nature Biotechnology, 37(4). https://doi.org/10.1038/s41587-019-0083-5
- Malmegrim, K. C. R., Picanço-Castro, V., Pereira, C. G., Covas, D. T., Porto, G. S., & Swiech, K. (2019). Emerging CAR T cell therapies: clinical landscape and patent technological routes. Human Vaccines & Immunotherapeutics, 16(6). https://doi.org/10.1080/21645515.2019.1689744
- Kano, S., & Kawai, Y. (2025). Expanding the concept of drug lifecycle management to chimeric antigen receptor T-cell products through product-patent linkage analysis. World Patent Information, 81. https://doi.org/10.1016/j.wpi.2025.102357
- Constantinescu, C., Gulei, D., Bergþorsson, J. Þ., Coliţă, A., Tănase, A., Tomuleasa, C., Greiff, V., & Constantinescu, R. (2023). Pitfalls in patenting academic CAR-T cells therapy. Expert Opinion on Therapeutic Patents, 33(6). https://doi.org/10.1080/13543776.2023.2220883
- U.S. Court of Appeals for the Federal Circuit (Aug. 26, 2021). Juno Therapeutics, Inc. v. Kite Pharma, Inc., 10 F.4th 1330. https://www.cafc.uscourts.gov/opinions-orders/20-1758.opinion.8-26-2021_1825257.pdf
- Holman, C. M. (2021). In Juno v. Kite the Federal Circuit strikes down patent directed towards pioneering innovation in CAR T-cell therapy. Biotechnology Law Report, 40(6). https://doi.org/10.1089/blr.2021.29252.cmh